
Blogs
PW Consulting: Global Drill Stabilizer Market to Hit $1,342.9M by 2032, 5.35% CAGR from 2025
By pmarketresearch, 2026-09-16
Navigating the 2026 Landscape: Strategic Insights from the Worldwide Drill Stabilizer Market
The global energy sector is currently navigating a complex transition period characterized by technological evolution, fluctuating raw material costs, and shifting geopolitical priorities. Within this volatile environment, the drill stabilizer market stands out as a critical barometer for upstream activity. As operators balance the need for efficient borehole construction with cost containment, understanding the trajectory of stabilizer demand is no longer optional—it is essential for strategic planning. Our latest comprehensive study, the Worldwide Drill Stabilizer Market Research, offers a granular look at the forces shaping this industry from 2026 through 2032.
This report is designed not merely as a data repository but as a strategic tool for executive decision-makers. By synthesizing historical performance data with forward-looking projections, we provide a clear view of where capital should be allocated and where risks may emerge. The following analysis highlights the core findings and strategic value embedded in our latest research, offering a preview of the intelligence available to subscribers.
Stabilizer Bars Market
Market Trajectory and Growth Dynamics
The drill stabilizer market has demonstrated resilience and steady expansion over the past half-decade. Analysis of historical data from 2020 to 2025 reveals a sector that has recovered strongly from earlier volatility, reaching a significant revenue milestone in the base year of 2025. The market size in 2025 stood at approximately 932.4 million USD, reflecting a compound annual growth rate that underscores consistent demand from global drilling operations.
Looking ahead to the forecast period of 2026 to 2032, the market is projected to continue its upward trajectory. Our models anticipate the market value will reach roughly 1342.9 million USD by the end of 2032. This growth corresponds to a CAGR of 5.35 percent over the forecast period. This moderate yet robust growth rate suggests a maturing market that is expanding in line with broader oilfield services trends rather than experiencing the boom-and-bust cycles typical of commodity markets. For investors and industry stakeholders, this indicates a stable environment for long-term capital deployment, provided that operational efficiencies are maintained.
It is important to note that the 2026 projection shows a slight adjustment from the 2025 base, reflecting current economic headwinds and inventory corrections. However, the rebound expected in subsequent years highlights the underlying essentiality of stabilizers in modern drilling assemblies. As drilling depths increase and well trajectories become more complex, the role of downhole stability tools becomes increasingly non-negotiable.
Technological and Material Foundations
The performance and cost structure of drill stabilizers are heavily dependent on material science and engineering specifications. Our research delves deep into the manufacturing inputs that define market competitiveness. A primary driver in this sector is the reliance on high-strength alloy steels, specifically grades such as AISI 4145H mod. These materials are chosen for their ability to withstand extreme downhole pressures and temperatures while maintaining structural integrity.
However, the supply chain for these raw materials has faced notable pressure. In late 2025, US structural steel and hot-rolled coil prices experienced upward pressure, with major producers like Nucor raising base prices to $910 per short ton. Simultaneously, global steel prices showed volatility, with scrap steel prices rising significantly in key regions. For stabilizer manufacturers, these input cost fluctuations directly impact margins and pricing strategies. Our report analyzes how leading companies are mitigating these risks through long-term supply contracts, material innovation, or price pass-through mechanisms.
Beyond raw materials, the technical function of stabilizers remains central to their market value. These components are critical within bottom hole assemblies for maintaining borehole trajectory, reducing vibration, and improving drilling efficiency in both vertical and directional wells. As drilling environments become more demanding, the demand for specialized variants, such as non-magnetic stabilizers for measurement-while-drilling operations or sleeve-type stabilizers for replaceable durability, is evolving. Understanding the performance differentiation between these types is crucial for procurement teams aiming to optimize wellbore quality.
Worldwide Drill Stabilizer Market
Competitive Landscape and Key Players
The market structure is characterized by a mix of specialized manufacturers and broader oilfield service providers. Our analysis indicates a moderately concentrated market, with the top three players holding a significant share of the revenue pool. This concentration suggests that while there is room for niche players, scale and technological capability remain key barriers to entry. The top five companies collectively command more than half of the market revenue, indicating strong brand loyalty and established supply chains among major operators.
Several key companies define the current competitive arena. Based in the United States, Stabil Drill operates as part of Superior Energy Services, focusing on custom-engineered solutions and maintaining a large rental fleet for demanding oil and gas drilling programs. Their strategy emphasizes flexibility and rapid deployment, catering to operators who require immediate access to high-quality tooling without heavy capital expenditure on assets.
Drilling Tools International offers a comprehensive range of stabilizers, including their ClearPath and Integral Blade series. Their product diversity allows them to serve a wide spectrum of drilling applications, from standard vertical wells to complex directional projects. On the other side of the Pacific, Chinese manufacturers are making significant inroads. Vigor Drilling Oil Tools And Equipment Co., Ltd. specializes in premium stabilizers with API certifications and hard facing options, leveraging cost-effective manufacturing to compete globally. Similarly, Landrill Oil Tools and Saigao Group bring over 15 years of experience in integral spiral blade string stabilizers, focusing on preventing hole deviation while maintaining competitive pricing.
Other notable participants include Gulf States Drilling Supply, which focuses on durability and performance in re-builting services, and Welong Oil Tools, which emphasizes strict quality control standards. Tianhe Oil Group rounds out the landscape with a focus on replaceable sleeve stabilizers. The competition among these entities is not just on price but on reliability, delivery speed, and the ability to customize tools for specific geological conditions. Recent developments, such as product information updates from Torrent Oil Tools and catalog updates from Sinodrills, highlight the industry's focus on educating customers about the right stabilizer choices for diverse environments.
Regional and Application Insights
Understanding where demand originates is vital for market entry or expansion strategies. Our research categorizes the market across five major regions, each with distinct drivers. North America remains a dominant force, driven by intensive onshore activity and established infrastructure. The Middle East and Africa also represent a substantial portion of the market, correlating with major national oil company projects and extensive offshore developments. Asia Pacific holds a significant share, reflecting the growing energy consumption and domestic drilling needs in emerging economies. Europe and Latin America contribute additional volumes, often tied to specific exploration blocks and mature field enhanced recovery projects.
In terms of application, the market is primarily driven by onshore drilling activities, which account for the larger share of revenue. This is consistent with the global trend of focusing on accessible reserves and cost-effective extraction methods. However, offshore drilling remains a critical segment, particularly for deepwater and ultra-deepwater projects where stabilizer performance is linked directly to safety and well integrity. The interplay between these two application types influences production planning; for instance, a slowdown in offshore capital expenditure can be partially offset by sustained onshore activity. Our report details how these segments interact and provides forecasts that account for the differing cyclicality of onshore versus offshore investment.
Regulatory and Quality Standards
Compliance is a non-negotiable aspect of the drill stabilizer market. Manufacturers must adhere to rigorous industry standards, particularly those set by the American Petroleum Institute. API standards, such as API 7-1 for rotary shouldered connections and various material specifications, ensure that equipment can withstand the harsh conditions of oilfield operations. Our research highlights the importance of these certifications in market access. Suppliers who fail to meet these standards risk exclusion from supply chains involving major international operators. Furthermore, as environmental and safety regulations tighten globally, the documentation and traceability of materials used in stabilizers are becoming increasingly important. Companies that can demonstrate compliance and quality control throughout their manufacturing process gain a distinct competitive advantage.
Strategic Value for 2026 Decision-Making
Why does this market research matter for the 2026 business cycle? The answer lies in the convergence of cost, technology, and demand. With steel prices volatile and energy transition pressures mounting, operators are scrutinizing every component of the drilling process. Stabilizers are not merely commodity items; they are engineering solutions that affect the total cost of drilling a well. A stabilizer failure can lead to non-productive time, deviated wells, and increased repair costs, which far outweigh the initial purchase price.
Our report equips stakeholders with the intelligence needed to navigate this complexity. For manufacturers, it identifies growth corridors and product segments ripe for innovation, such as non-magnetic or specialized sleeve types. For investors, it clarifies the competitive positioning of key players and the health of the demand pipeline across different regions. For procurement officers, it offers benchmarks for pricing and quality expectations in a fluctuating raw material environment.
The insights provided go beyond surface-level numbers. We examine the strategic moves of companies like Stabil Drill and Vigor Drilling to understand how they are positioning themselves for the next seven years. We analyze the impact of recent product information updates and catalog revisions as indicators of where the industry is placing its emphasis. This level of detail allows for nuanced strategy formulation rather than reliance on generic industry assumptions.
Conclusion
The Worldwide Drill Stabilizer Market is poised for steady growth, underpinned by essential drilling activities and technological advancements. However, realizing value in this market requires a deep understanding of the underlying dynamics, from steel pricing volatility to regional demand shifts and competitive maneuvers. Our latest research provides the comprehensive intelligence necessary to make informed decisions in 2026 and beyond.
To access the full depth of this analysis, including detailed segmentation data, specific country-level forecasts, and comprehensive company profiles, we invite you to explore the complete report. The data points summarized here represent only the tip of the iceberg. The full intelligence suite offers the actionable clarity needed to secure your position in the evolving energy landscape.
For detailed analysis of this topic, please visit the official page: Worldwide Drill Stabilizer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Acute Ischemic Stroke Market Set to Hit $18.2B by 2032, 7.82% CAGR
By pmarketresearch, 2026-09-16
Charting the Course for Growth: Strategic Imperatives in the Worldwide Acute Ischemic Stroke Market (2026-2032)
Executive Overview
The landscape of acute ischemic stroke (AIS) intervention is undergoing a definitive transformation, driven by technological innovation, evolving clinical guidelines, and shifting demographic realities. As we move beyond 2026, stakeholders across the medical device and pharmaceutical ecosystems must navigate a market characterized by robust growth and intensifying competition. This article serves as a strategic primer based on our latest comprehensive research, offering a high-level view of the forces shaping the industry while underscoring the depth of intelligence available to informed decision-makers.
Our analysis tracks the market trajectory from a base year of 2025 through a forecast horizon extending to 2032. The data indicates a compelling expansion path, with the global market reaching approximately $10.75 billion in 2025 and projected to climb significantly thereafter. This growth is not merely linear; it reflects fundamental shifts in treatment protocols, reimbursement landscapes, and device adoption rates. For executives and investors, understanding the nuance behind these figures is critical for capital allocation, product portfolio strategy, and market entry decisions.
However, macro-level numbers only tell part of the story. True strategic advantage lies in dissecting the underlying drivers—from regional variance in adoption rates to the specific competitive moves of key incumbents. This overview highlights the critical dynamics at play, but the full intelligence required to operationalize these insights requires a deeper dive into our proprietary segmentation and forecasting models.
Worldwide Acute Ischemic Stroke Market
Market Trajectory and Growth Drivers
The recent historical performance of the AIS market demonstrates resilience and accelerating demand. Between 2020 and 2025, the sector expanded from roughly $7.42 billion to over $10.75 billion. This upward momentum is expected to continue, with the forecast period through 2032 suggesting a sustained compound annual growth rate that underscores the increasing reliance on interventional neurology solutions. The projected revenue figures for the late forecast period indicate a substantial increase in total addressable market size, driven by both volume growth and higher-value device utilization.
Key Catalysts for Expansion
Several structural factors are converging to support this growth trajectory:
- Demographic Shifts: The prevalence of stroke risk factors is rising globally. Industry projections suggest that AIS incidence could rise significantly by 2030, particularly in aging populations across the US and Europe, creating a larger patient pool for intervention.
- Guideline Evolution: Recent updates from major clinical bodies, such as the AHA/ASA 2024 guidelines, have expanded the eligibility window for thrombectomy procedures to 24 hours for select patients. This change effectively increases the number of treatable patients per capita, directly influencing device and drug utilization volumes.
- Technological Advancement: Innovation cycles are shortening. The introduction of next-generation devices, including flow diverters for complex aneurysms associated with AIS and enhanced aspiration systems, is driving adoption among clinicians seeking better outcomes and faster procedure times.
- Regulatory and Reimbursement Support: Favorable policy changes are reducing financial barriers. For instance, recent updates to CMS reimbursement rules for eligible thrombectomy devices in the inpatient prospective payment system have improved the economic viability of advanced interventions for hospitals.
While these drivers paint a positive picture, they also introduce complexity. The interplay between regulatory approvals, reimbursement rates, and clinical adoption varies significantly by geography and care setting. Our full report deconstructs these variables to provide actionable forecasts, but the headline message is clear: the demand curve is shifting upward, and organizations must position themselves to capture value in this expanding space.
Cerebrovascular Accident Drug Market
Competitive Landscape and Strategic Positioning
The AIS market is characterized by a moderately concentrated competitive environment where innovation and brand loyalty play pivotal roles. Market concentration metrics indicate that a significant portion of revenue is generated by a core group of established players. This concentration suggests high barriers to entry for new competitors, emphasizing the importance of strategic partnerships, robust clinical evidence, and comprehensive product portfolios for organizations looking to gain share.
Profiles of Key Incumbents
Leading companies are actively shaping the market through product launches, regulatory clearances, and clinical evidence generation. Our research tracks the strategic moves of pivotal organizations:
- Stryker Corporation: Continues to lead in mechanical thrombectomy with advanced retrievers and catheters. Recent moves include the launch of flow diverters aimed at stroke prevention in complex cases, signaling a strategy to address broader neurovascular needs beyond acute clot removal.
- Medtronic plc: Maintains a strong position with its revascularization devices and aspiration systems. Positive long-term study data presented recently reinforces the clinical value proposition of their core assets, strengthening their competitive moat.
- Johnson & Johnson (Cerenovus): Focuses on next-generation revascularization platforms. Recent FDA approvals for updated devices highlight their commitment to iterative innovation in large vessel occlusion treatments.
- Penumbra, Inc.: Specializes in aspiration thrombectomy technologies. Recent regulatory clearances for enhanced aspiration systems demonstrate their focus on improving procedural efficiency and speed, key metrics for stroke care workflows.
- Other Notable Players: Companies such as Balt USA, Terumo Corporation, MicroVention, and Rapid Medical are also active, offering specialized solutions ranging from guidewires and access devices to integrated aspiration systems. Regional expansions, such as securing CE Marks for European markets, indicate aggressive strategies to capture international share.
Strategic interaction among these players involves not just product competition but also competition for clinical mindshare and formulary positioning. Recent developments, including breakthrough device designations granted to multiple new systems in 2025, suggest that the pace of innovation will remain high. Understanding the specific pipeline status and launch timelines of competitors is essential for anticipating market shifts, details of which are exhaustively covered in our full analysis.
Market Dynamics: Reimbursement, Regulation, and Supply Chain
Beyond clinical factors, external dynamics heavily influence market accessibility and profitability. The interplay of policy and logistics creates both opportunities and risks that must be managed proactively.
Reimbursement and Economic Factors
Reimbursement policies are a primary determinant of procedure volume. Recent adjustments to Medicare reimbursement rates for specific thrombectomy devices have improved the financial outlook for hospitals performing these procedures. However, reimbursement landscapes are fragmented globally, and navigating regional payment models requires localized intelligence. Changes in coding and coverage can rapidly alter the adoption curve for new technologies, making real-time tracking of policy updates vital for commercial success.
Regulatory Environment
Regulatory pathways are evolving to encourage innovation. The granting of breakthrough device designations to multiple AIS thrombectomy systems in 2025 reflects a regulatory environment open to novel solutions that offer significant clinical advantages. However, compliance requirements remain stringent. Organizations must balance speed-to-market with rigorous clinical validation to maintain trust and market access.
Supply Chain Considerations
Geopolitical factors are beginning to impact supply chain stability. Recent tariff increases on certain neurovascular components sourced from specific regions add complexity to procurement and cost structures. Manufacturers and distributors must assess their supply chain resilience and consider localization or diversification strategies to mitigate cost pressures and ensure uninterrupted device availability.
Clinical Integration and Workflow
The expansion of treatment windows and the push for faster intervention times require seamless integration of devices into hospital workflows. Products that offer ease of use, compatibility with existing infrastructure, and improved procedural efficiency are gaining preference. This trend favors vendors that provide comprehensive training and support, further entrenching market leaders with established service networks.
Segmentation Overview: Treatment and End-User Focus
The market is segmented by treatment type and end-user setting, each with distinct growth characteristics. In the treatment category, mechanical thrombectomy devices and thrombolytic drugs represent the largest value pools. The choice between device-based intervention and pharmacological treatment often depends on patient presentation, hospital capability, and clinical guidelines. Device-based interventions, particularly mechanical thrombectomy, are seeing accelerated growth due to efficacy data and guideline support, whereas thrombolytic drugs remain a critical component of the standard of care, especially in settings where advanced imaging or intervention suites are not immediately available.
Accessory devices, including carotid stents, balloons, and distal access tools, constitute a significant portion of the ecosystem, enabling successful interventions. Their adoption is tied to the volume of primary interventional procedures, creating a symbiotic growth dynamic within the product portfolio.
From an end-user perspective, hospitals remain the dominant care setting for AIS interventions, reflecting the need for comprehensive emergency and critical care infrastructure. However, specialty clinics and ambulatory surgical centers are emerging as important venues, particularly for follow-up care and selected procedures. The growth of these alternative settings is influenced by healthcare system restructuring, cost containment pressures, and the push to decentralize care where clinically appropriate. Our report analyzes the specific volume contributions and growth rates across these segments, providing clarity on where value is concentrating.
Regional Perspectives
Geographically, the market exhibits diverse maturity levels and growth potentials. North America continues to represent a significant revenue contributor, supported by high adoption rates, favorable reimbursement environments, and the presence of key innovators. Europe follows as a major market, driven by strong clinical networks and increasing uptake of advanced devices. The Asia Pacific region is often highlighted for its growth potential, linked to expanding healthcare infrastructure and rising disease burden, though adoption dynamics vary widely between developed and developing nations within the region.
Latin America and the Middle East and Africa represent smaller but evolving markets, where access to advanced neurovascular care is improving gradually. Strategic expansion into these regions requires tailored approaches addressing local reimbursement, training, and device distribution challenges. Our research provides granular regional forecasts that help organizations prioritize investment based on risk-adjusted return profiles, though specific regional breakdowns are reserved for the full report to protect proprietary insights.
Conclusion: Strategic Imperatives for 2026 and Beyond
The Worldwide Acute Ischemic Stroke Market presents a landscape of substantial opportunity layered with complexity. The convergence of demographic trends, clinical guideline expansions, and technological innovation creates a favorable demand environment. However, realizing value in this market requires more than recognizing growth trends; it demands a nuanced understanding of competitive positioning, reimbursement dynamics, and regional variability.
Organizations must ask critical questions: How do our product pipelines align with expanding treatment windows? Are we prepared for supply chain disruptions and cost pressures? How can we leverage clinical data to differentiate in a competitive field? Answering these questions requires access to detailed, forward-looking intelligence that goes beyond surface-level statistics.
This overview has highlighted the macro dynamics and strategic themes defining the AIS market. Yet, the decisions you make in 2026 depend on precision. You need specific forecasts, competitive benchmarking, and segmentation analysis that can inform product launches, pricing strategies, and market entry plans. Our full market research report delivers this depth, offering the comprehensive intelligence necessary to navigate the upcoming years with confidence.
For stakeholders committed to capturing growth in the acute ischemic stroke sector, the next step is to engage with the detailed data. We invite you to access the complete study to unlock the full spectrum of insights, from granular market sizing to actionable competitive profiles, ensuring your strategy is built on the strongest possible foundation.
For detailed analysis of this topic, please visit the official page: Worldwide Acute Ischemic Stroke Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Choroideremia Market Hits $38.42M in 2025, Projected to Reach $278.01M by 2032
By pmarketresearch, 2026-09-16
Navigating the Therapeutic Frontier: Strategic Insights from the Worldwide Choroideremia Treatment Market 2026–2032
The global landscape for choroideremia treatment is undergoing a structural transformation. Once confined to supportive care and low-vision management, the market is now defined by a rapidly maturing pipeline of gene therapies, optogenetic approaches, and small-molecule vision-restoration candidates. For pharmaceutical executives, investors, and clinical strategy leaders, understanding this inflection point requires more than a snapshot of trial readouts. It demands a rigorous assessment of commercial viability, regulatory asymmetry, manufacturing bottlenecks, and the shifting economics of ultra-rare ocular indications. The Worldwide Choroideremia Treatment Market market research report has been designed specifically to meet that need, translating complex clinical and regulatory developments into actionable strategic intelligence for 2026 decision-making.
A Market in Accelerated Expansion
Historical tracking from 2020 through 2025 reveals a consistent upward trajectory in market revenue, reflecting growing clinical engagement, expanded trial activity, and heightened institutional interest in inherited retinal diseases. Building on that foundation, the forecast window from 2026 through 2032 points to a sustained compound annual growth rate of approximately 32.65 percent, measured in U.S. dollars and expressed in millions. This growth profile is not merely a function of patient volume; choroideremia affects roughly one in 50,000 males, placing it firmly within the ultra-rare disease category. Instead, the expansion is being driven by a combination of therapeutic innovation, orphan-drug incentives, and a recalibration of how developers and payers evaluate clinical endpoints for progressive retinal degeneration.
For strategy teams, the macroeconomic signal is clear: the addressable commercial horizon is widening, but the path to commercialization remains highly fragmented. Revenue trajectories are being shaped by trial design choices, delivery modality selection, regional regulatory tolerance, and the financial endurance of small and mid-cap biotechnology firms. The report structures this complexity into a coherent analytical framework, allowing stakeholders to stress-test assumptions about adoption curves, reimbursement readiness, and the timing of potential product launches across distinct therapeutic modalities.
Why 2026 Requires a Refreshed Strategic Lens
The year 2026 represents a pivotal calibration point. Several programs that dominated earlier development conversations have reached definitive inflection points, while others are entering new regulatory and clinical phases. The market research report situates these developments within a forward-looking commercial architecture, helping organizations answer the questions that matter most to capital allocation and portfolio planning: Which therapeutic approaches are most likely to navigate endpoint requirements? Where do regional regulatory frameworks create divergent approval pathways? How do manufacturing and vector-production constraints influence scalability and cost structures?
A central theme woven throughout the analysis is the regulatory asymmetry between major jurisdictions. Data reviewed in the report highlights that choroideremia gene therapy candidates have historically faced challenges in meeting primary endpoint thresholds that require substantial best-corrected visual acuity improvements. At the same time, alternative regulatory expectations in certain regions may accept more moderate gains as clinically meaningful, potentially enabling region-specific commercialization strategies. Understanding where those tolerances intersect with trial design, patient selection, and long-term follow-up data is essential for companies evaluating launch sequencing, partnership structures, and geographic prioritization.
What the Report Delivers: Content, Structure, and Operational Value
The Worldwide Choroideremia Treatment Market study is built for practitioners who need defensible inputs for pricing strategy, market-entry timing, pipeline benchmarking, and partnership evaluation. Rather than functioning as a passive data repository, the report integrates clinical context, regulatory mapping, and commercial modeling into a single decision-support instrument. Executive and analytical audiences will find structured coverage across the following operational dimensions:
- Historical baseline and forecast architecture: A detailed reconstruction of market revenue from 2020 through 2025, followed by forward-looking projections through 2032. This provides a grounded reference for scenario planning, sensitivity testing, and investment hurdle-rate calibration.
- Therapeutic modality segmentation: The analysis breaks down the treatment landscape by gene therapy, vitamin and nutritional supplementation, and low-vision aids. Each segment is examined through the lens of clinical rationale, development maturity, reimbursement potential, and commercial feasibility, giving readers a comparative view of where value creation is most concentrated.
- End-user and care-delivery mapping: Specialty hospitals, ophthalmic clinics, and ambulatory surgery centers are evaluated as distinct adoption environments. The report assesses how procedure setting, physician adoption patterns, and infrastructure requirements shape demand dynamics for advanced ocular therapies.
- Regional framework and market concentration: North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa are contextualized as separate strategic arenas, each with its own regulatory rhythm, reimbursement logic, and competitive intensity. The report also examines concentration dynamics among leading participants, highlighting how dominance is distributed across the pipeline and what that implies for new entrants.
- Regulatory, reimbursement, and manufacturing realities: Orphan-drug pathways, advanced therapy medicinal product frameworks, and endpoint expectations are mapped alongside the practical constraints of AAV vector production, GMP manufacturing consistency, and the financial exposures faced by developers targeting ultra-rare indications.
- Competitive benchmarking and recent catalysts: Company-level profiles are paired with recent developmental milestones, enabling readers to track how asset transfers, trial progress, and regulatory designations are reshaping the field in real time.
By integrating these layers, the report serves as a reference point for both near-term tactical decisions and multi-year strategic planning. It is particularly useful for teams evaluating co-development structures, licensing opportunities, investor narratives, or internal pipeline prioritization in ocular and rare-disease portfolios.
Competitive Field: Who Is Shaping the Next Wave
The competitive landscape is defined by a mix of biotech innovators, nonprofit research entities, and legacy programs that have been repositioned through asset transfers. The report provides structured profiles and activity tracking for the organizations that are most actively influencing development momentum and market expectations.
Kiora Pharmaceuticals, based in Encinitas, California, is advancing KIO-301, a small-molecule photoswitch intended to restore visual function in inherited retinal diseases. While its primary development focus has centered on retinitis pigmentosa, the report examines the explicit potential expansion pathway into choroideremia, alongside recent progress in functional vision endpoint validation and ongoing Phase 2 dosing activity. The analysis highlights why a non-gene-therapy modality could alter both the risk profile and the commercial architecture of the market.
Ray Therapeutics, headquartered in Berkeley, California, is developing RTx-015, an optogenetic channelrhodopsin-based gene therapy aimed at vision restoration. Its Phase 1 ENVISION trial is evaluating intravitreal delivery and includes choroideremia among the conditions under assessment. Recent regulatory recognition, including FDA RMAT designation, is treated within the report as a signal of momentum, but also as a catalyst that raises expectations for safety, delivery consistency, and longer-term efficacy readouts.
The Choroideremia Research Foundation, located in Springfield, Massachusetts, has emerged as a distinctive force in the field following its acquisition of Spark Therapeutics’ SPK-7001 gene therapy assets in 2025. The report details how the foundation is now analyzing long-term Phase I/II clinical trial data and natural history studies to identify patient-relevant endpoints that could support future development or regulatory use. This nonprofit-led asset stewardship model is examined not only as a clinical story, but also as a structural precedent for how discontinued or deprioritized programs can retain commercial and scientific relevance.
Spark Therapeutics’ SPK-7001 program, which used an AAV2-hCHM-101 subretinal gene therapy approach, previously demonstrated safety objectives with some self-reported stabilization. Following program discontinuation, the assets were transferred to the foundation, and the report uses this transition to illustrate how intellectual property, biological materials, orphan designations, and clinical data can retain value even when a commercial sponsor steps away.
The report also addresses programs that illustrate the inherent risk profile of the space. Biogen’s earlier work on timrepigene emparvovec, including the Phase 3 STAR trial, did not meet the primary endpoint threshold of a substantial visual acuity improvement, and active commercial pursuit of the program was discontinued. Similarly, 4D Molecular Therapeutics advanced an intravitreal AAV gene therapy into Phase 1 before terminating the program in early 2025 to prioritize other pipeline assets. These cases are analyzed as cautionary reference points for endpoint sensitivity, delivery modality selection, and the capital intensity of ocular gene therapy development.
Worldwide Choroideremia Treatment Market
Regulatory, Reimbursement, and Manufacturing Dynamics as Strategy Drivers
A defining feature of the current market is the tension between scientific ambition and commercial realism. The report treats regulation, reimbursement, and manufacturing not as background context, but as primary drivers of strategic choice. Gene therapy programs for choroideremia must navigate endpoint expectations that can vary by jurisdiction, and the analysis notes that differences in how primary endpoints are defined and interpreted may lead to region-specific approval pathways. This matters for companies deciding where to seek initial authorization, how to design confirmatory evidence packages, and which clinical signals to prioritize during trial execution.
Reimbursement dynamics add another layer of complexity. High development and manufacturing costs associated with AAV-based gene therapies create financial risk for smaller biotechnology firms, especially when targeting ultra-rare populations. The report explores how these cost structures influence pricing expectations, partnership requirements, and the sustainability of standalone commercialization strategies. It also examines how orphan-drug designations and advanced therapy frameworks can support development, while still leaving unresolved questions about long-term access, budget impact, and payer willingness to absorb premium pricing for narrowly indicated therapies.
On the operational side, AAV vector production and consistent GMP manufacturing are identified as key constraints affecting both cost and scalability. Whether delivery is subretinal or intravitreal, the ability to produce reliable, GMP-grade vector material at appropriate scale remains a critical determinant of development continuity and eventual commercial readiness. The report contextualizes these manufacturing realities alongside the broader pipeline, helping readers assess which programs are better positioned to manage supply-chain risk and which may face structural headwinds as they advance.
How Stakeholders Can Use the Report in 2026
For executive teams and strategy functions, the report is designed to support several high-value use cases. Portfolio planners can use the forecast architecture and modality segmentation to compare risk-adjusted opportunity across gene therapy, optogenetic, photoswitch, and supportive-care pathways. Business development teams can leverage company profiles and recent catalyst tracking to identify partnership targets, asset-acquisition opportunities, and trial-design benchmarks. Regulatory and market-access strategists can draw on the jurisdictional analysis to anticipate endpoint scrutiny, prepare for divergent approval expectations, and frame reimbursement narratives that reflect both clinical promise and economic constraint. Investors and financial analysts can use the market concentration discussion and historical baseline to interrogate growth assumptions, competitive exposure, and the durability of emerging leads.
Worldwide Refsum Disease Treatment Market
Just as importantly, the report is built to be revisited. The choroideremia treatment landscape is evolving quickly, and the strategic questions that matter today will continue to shift as trials report, assets change hands, and regulatory expectations mature. By grounding those dynamics in structured market data and competitive context, the study gives organizations a stable reference point for interpreting new developments as they emerge.
Conclusion: From Clinical Promise to Commercial Clarity
The worldwide choroideremia treatment market is no longer defined solely by the absence of approved disease-modifying options. It is increasingly shaped by a set of competing scientific approaches, uneven regulatory expectations, and a financial environment that rewards both innovation and disciplined execution. The Worldwide Choroideremia Treatment Market market research report translates that complexity into a structured, decision-ready format, giving stakeholders the analytical grounding needed to plan with confidence in 2026 and beyond. For teams seeking a deeper look at segmentation, regional dynamics, concentration metrics, and the full set of company-level findings, the complete report provides the granular intelligence necessary to convert market insight into strategic action.
For detailed analysis of this topic, please visit the official page: Worldwide Choroideremia Treatment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Cold Formed Steel Frame Market Hits $39.86B in 2025, Projected 5.29% CAGR to 2032
By pmarketresearch, 2026-09-16
Navigating the Next Chapter: Why the 2026 Cold-Formed Steel Frame Market Demands Strategic Foresight
The global construction landscape is undergoing a structural recalibration. As urbanization accelerates and sustainability mandates tighten, cold-formed steel (CFS) framing has moved from a niche alternative to a mainstream backbone of modern building systems. For executives, investors, and supply chain leaders, the question is no longer whether CFS will capture additional market share, but how to position portfolios, pricing strategies, and partnership networks ahead of the inflection points visible in the 2026–2032 forecast window. Our newly updated Worldwide Cold Formed Steel Frame Market research is designed precisely for that moment of decision. This briefing outlines the strategic contours of the study, the competitive forces reshaping the space, and the macro dynamics that will separate resilient operators from reactive followers.
A Market at the Intersection of Scale and Structural Shift
Over the past half-decade, the global CFS framing market has demonstrated a resilient upward trajectory, with aggregate revenue climbing from the mid-$31 billion range in 2020 to nearly $40 billion by the 2025 base year. That momentum is projected to carry the market past the $42 billion threshold in 2026, before a series of compounding growth phases push the top line toward the high-$50 billion territory by the end of the forecast period. The implied compound annual growth rate across the full horizon sits at 5.29 percent, a figure that signals durable expansion rather than speculative volatility.
Worldwide Cold Formed Steel Frame Market
What makes this trajectory strategically meaningful is not the headline number alone, but the velocity and consistency of the expansion. The 2020–2025 historical window captures a market absorbing pandemic-era supply disruptions, evolving code frameworks, and a gradual but decisive shift toward lighter, prefabricated building systems. From 2026 onward, the forecast model reflects a more mature demand profile: project pipelines that are less sensitive to single-cycle fluctuations, material substitutions that are increasingly evaluated on lifecycle cost rather than first cost, and regional development programs that favor speed-to-completion and labor efficiency. For strategy teams, that means CFS is no longer a defensive hedging play against wood or concrete constraints; it is an offensive platform for capturing value in mid-rise, high-rise, and modular construction segments where precision engineering and schedule certainty carry premium margins.
What This Research Delivers: An Executive-Ready Intelligence Architecture
A market study earns its place on a strategy team’s desk only when it translates complexity into actionable architecture. Our analysis is structured to do exactly that. Rather than presenting a monolithic top-line projection, the report disaggregates the market into product-type, application, and regional dimensions, allowing leadership to isolate growth vectors that align with specific capabilities, procurement footprints, and risk tolerances. Decision-makers can examine how C-shaped sections, U-shaped track sections, Z-shaped sections, and hat channels and accessories each carve out distinct demand profiles across commercial, residential, industrial, and institutional end uses.
Beyond segmentation, the study embeds the operational realities that determine execution success. The forecast framework is paired with an assessment of supply chain dependencies, including the behavior of primary feedstock inputs that influence coil pricing and mill pass-through dynamics. It also maps the regulatory cadence that shapes specification behavior, from updated structural design specifications to the evolving code-compliance expectations that govern framing installation, load capacity, and span performance. Sustainability is treated not as a narrative sidebar but as a procurement filter: environmental product declarations, embodied carbon considerations, and lifecycle compliance pathways are evaluated for how they alter specification priority in bids where green building certification and low-carbon procurement clauses are becoming standard.
Perhaps most importantly, the report ties market sizing to the competitive behaviors that generate it. By examining how key manufacturers position themselves across geographies, product families, and application verticals, the study provides a lens for assessing where consolidation pressure is likely to intensify, where technology-driven differentiation—such as precision roll-forming and software-assisted framing design—creates defensible moats, and where distributor and fabricator relationships will determine speed of market penetration.
The Competitive Landscape: Scale, Specialization, and the Push for Code-Compliant Advantage
The CFS framing arena is populated by players whose strategic postures span the full spectrum from commodity-scale steel supply to highly specialized framing system engineering. At one end sit large integrated steel producers whose coil and material outputs form the foundational input stack for the framing ecosystem. These firms benefit from vertical integration, which can translate into better cost visibility and supply reliability when feedstock markets become volatile. Their global reach also means they are often the first to respond to demand signals in multiple regions, shaping the pricing environment that downstream formers and framing manufacturers must navigate.
At the other end of the spectrum are specialist roll-formers, prefabricated system providers, and technology-forward framing solution companies. Some have built reputations around precision-formed sections and accessories tailored for mid-rise and high-rise commercial projects, often in close alignment with industry associations that publish code-compliant guides and load/span references. Others have leaned into sustainability as a differentiator, publishing environmental product declarations and engineering low-embodied-carbon framing systems that meet emerging procurement requirements. A further cluster of players focuses on connectors, bridging, and accessory systems optimized for modular and rapid construction workflows, where the value proposition is less about metal volume and more about installation speed, structural integration, and labor productivity.
This diversity matters because the market is not consolidating into a single model of competition. Instead, it is stratifying. Vertically integrated material suppliers can compete on cost stability and volume availability. Specialized formers compete on specification inclusion, product consistency, and technical support. Software-linked framing solution providers compete on design-to-fabrication efficiency and the ability to accelerate project timelines. For executives evaluating partnership, acquisition, or capacity-expansion options, the relevant question is not which segment is largest, but which segment offers the best fit with a firm’s existing integration profile, geographic reach, and customer access. The research unpacks these positioning dynamics so that leadership can avoid the common mistake of assuming that share growth follows automatically from capacity growth.
Market Dynamics: Feedstock Volatility, Code Evolution, and the Sustainability Mandate
Three dynamic forces are shaping the strategic environment around CFS framing in 2026 and beyond. The first is the behavior of upstream material pricing. Hot-rolled coil, a primary feedstock input for many cold-formed products, has shown meaningful year-over-year movement, with recent spot indications reflecting construction and automotive demand pressures alongside broader mill economics. While framing manufacturers do not control coil pricing, they are deeply affected by its trajectory and by the timeliness of pass-through mechanisms, contract structures, and inventory strategies. In this environment, the firms that manage downside risk most effectively are those that combine supply diversification, forward visibility into specification pipelines, and pricing frameworks that preserve margins without forfeiting bid competitiveness.
The second force is regulatory and standards evolution. Updated technical guides and design specifications are tightening the link between product performance, installation practice, and code compliance. When associations release revised framing guides aligned with newer building codes and when design specifications are refreshed with updated load and span parameters, the immediate effect is not just technical; it is commercial. Specification behavior shifts, engineering teams recalibrate project assumptions, and fabricators must ensure that their product range and quality systems remain aligned with the newest reference points. Companies that anticipate these updates and embed them into product development and sales enablement gain an edge in bids where compliance certainty and engineering support influence spec-in decisions.
The third force is sustainability as a specification driver. Environmental product declarations and low-embodied-carbon framing systems are increasingly relevant in project evaluations, particularly where contracts incorporate carbon-reduction targets or where building certification frameworks reward transparent lifecycle data. This does not mean sustainability is replacing cost or structural performance as primary selection criteria. It does mean that sustainability is becoming a gatekeeping attribute in a growing subset of commercial and institutional projects. Manufacturers that can demonstrate cradle-to-gate transparency, documented impact data, and code-compliant performance simultaneously are better positioned to compete in specification processes where multiple technically acceptable solutions are evaluated on total project value.
Why 2026 Decision-Making Requires a Forward-Looking Intelligence Framework
The 2026–2032 window is not a plain extrapolation of recent trends. It is a period in which regional development programs, material cost cycles, code refresh cycles, and sustainability procurement practices will interact in ways that create uneven growth across segments. Some product categories will benefit disproportionately from project type shifts. Some applications will see faster adoption where labor constraints and schedule pressure are most acute. Some regions will experience stronger momentum due to infrastructure spending patterns, urban densification, and the maturation of local fabrication ecosystems. Without a granular view of these interactions, strategy teams risk planning against an average that does not exist in practice.
This research is built to reduce that blindness. It gives leadership a structured way to test assumptions about where demand is most durable, which product families are most exposed to substitution risk, and how competitive intensity is likely to evolve as manufacturers adjust capacity, broaden accessory portfolios, and invest in design-to-build efficiency. It also provides context for financial planning: margin trajectories depend not only on end-demand volume but on input cost management, specification win rates, and the ability to move up the value chain through engineered systems rather than commodity sections alone.
How to Use This Study for Immediate Strategic Action
The report can be deployed in several practical ways. For corporate development and M&A teams, it offers a landscape map of who competes where, what capabilities matter most, and where consolidation or partnership logic may be strongest. For commercial and sales leadership, it clarifies which application verticals and product types present the clearest near-term opportunity and which require longer-cycle specification cultivation. For procurement and supply chain executives, it frames the feedstock and pricing environment in a way that supports hedging, contracting, and inventory decisions with greater confidence. For sustainability and regulatory affairs teams, it links market growth to the compliance and documentation requirements that increasingly shape project eligibility.
Most critically, the study is designed to support prioritization. Not every growth opportunity is equally accessible, and not every competitive threat is equally material. By separating headline momentum from segment-level drivers, the research helps decision-makers allocate capital, talent, and commercial attention to the areas where the next cycle of value creation is most likely to concentrate.
Light Gauge Steel Market
The Window Is Open, but the Detail Determines the Advantage
The global cold-formed steel frame market is expanding with enough scale and structural momentum to reward proactive strategy, but the payoff will go to those who understand the shape of that growth rather than merely its size. The macro arc is clear: demand is rising, the forecast horizon supports sustained expansion, and the competitive field is evolving across scale, specialization, and sustainability. What remains beneath the surface—and what this study is built to reveal—is the granular architecture of that expansion: where share is migrating, which product and application combinations carry the strongest forward demand, and how the leading manufacturers are positioning themselves to capture it. For executives who need to turn 2026 uncertainty into a defensible growth plan, the full analysis provides the intelligence layer required to move from observation to action.
For detailed analysis of this topic, please visit the official page: Worldwide Cold Formed Steel Frame Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Worldwide Glaucoma Diagnostics Market Hits $2.67B in 2025, Projected 5.01% CAGR to 2032
By pmarketresearch, 2026-09-16
Navigating the Next Wave: Strategic Imperatives in the Global Glaucoma Diagnostics Market
Blindness caused by glaucoma remains a pressing global health challenge, yet the market designed to detect and monitor it is evolving at an unprecedented pace. According to the latest Worldwide Glaucoma Diagnostics Market research by PW Consulting, the industry stands at a critical inflection point. With a projected revenue trajectory accelerating from USD 2.67 billion in 2025 to USD 3.82 billion by 2032, the sector is poised to compound at a steady 5.01 percent CAGR. For healthcare strategists, medical device executives, and investment professionals, this growth narrative is not merely a statistical forecast—it is a blueprint for where capital, innovation, and clinical adoption will converge over the next seven years.
Why 2026 Is a Make-or-Break Year for Glaucoma Diagnostics Strategy
The forecast horizon of 2026 through 2032 reveals more than incremental expansion; it maps a structural realignment in how glaucoma is screened, diagnosed, and tracked. Our analysis traces the market's historical arc from 2020 to 2025, capturing the resilience of demand even as supply chain volatility and regulatory shifts tested manufacturer agility. By 2024, total sector revenue had already crossed the USD 2.5 billion threshold, and the momentum into 2026 suggests a decisive shift toward integrated diagnostic workflows. This is the year where early adopters of AI-enabled imaging, wireless tonometry, and home-monitoring platforms will either secure clinical loyalty or risk ceding ground to competitors who master the operational and reimbursement complexities of modern ophthalmic care. Our report is engineered to help decision-makers separate signal from noise before the 2026 planning cycle locks in.
What the Research Delivers: Actionable Intelligence Beyond the Headlines
PW Consulting's Worldwide Glaucoma Diagnostics Market study is built for practitioners who need to act, not just observe. The report dissects the competitive landscape, product segmentation, end-user adoption patterns, and regional demand drivers through a lens of commercial applicability. Rather than offering a static snapshot, we provide a dynamic framework that connects clinical innovation to procurement realities, reimbursement pathways, and regulatory timelines.
- Product-Type Forecasts and Technology Adoption Curves: We evaluate how optical coherence tomography, tonometry platforms, fundus imaging, visual field analyzers, and emerging diagnostic modalities are shaping procurement priorities across care settings.
- End-User Demand Mapping: The research tracks investment and consumption patterns across ophthalmic clinics, hospital systems, and independent diagnostic centers, revealing where volume growth and margin opportunities are likely to concentrate.
- Regional Demand and Adoption Dynamics: Our geographic analysis contextualizes how mature markets and high-growth regions differ in procurement behavior, reimbursement maturity, and clinical workflow integration, helping leaders prioritize market-entry and expansion strategies.
- Regulatory and Reimbursement Intelligence: The report integrates evolving device classification requirements, coding structures, and reimbursement benchmarks that directly influence adoption velocity and purchasing decisions.
- Competitive Profiling and Strategic Posture Analysis: We examine how leading manufacturers are positioning their portfolios, accelerating product cycles, and leveraging clinical evidence to defend or expand share.
The Competitive Arena: How Incumbents and Challengers Are Shaping the Field
The glaucoma diagnostics ecosystem is defined by a concentrated yet highly contested competitive structure. Our analysis indicates that a relatively small group of established players commands a majority share of industry revenue, yet the margin for differentiation is expanding as technological innovation outpaces traditional procurement cycles. The leading ecosystem includes manufacturers from Germany, Japan, the United States, Switzerland, and Finland, each reinforcing distinct clinical value propositions.
German precision engineering continues to anchor a significant portion of the high-end imaging segment. Zeiss maintains a strong presence through its OCT systems and glaucoma-focused analytics, most recently underscored by the launch of the Cirrus 6000 OCT with enhanced glaucoma analytics software in October 2025. Nearby, Heidelberg Engineering has advanced its Spectralis platform with a dedicated glaucoma module for retinal nerve fiber layer analysis, and its November 2024 release of Spectralis 6.0 introduced AI-based glaucoma progression detection, reinforcing the shift toward algorithm-driven monitoring.
Japanese manufacturers are broadening the field with integrated imaging and functional testing portfolios. Topcon Healthcare's Triton swept-source OCT and Harmony perimeter platform have become central to glaucoma diagnostic workflows, and the company's June 2025 FDA 510(k) clearance for the Harmony2 AI-enabled visual field analyzer signals a decisive move toward intelligent perimetry. Nidek continues to reinforce the tonometry segment with instruments such as the TS-6100 tonometry system and Perceptra tonoplex, while Canon Medical Systems supports screening-oriented workflows through its RX2 non-contact tonometer and imageFIRST OCT. Kowa rounds out this cohort with its Prominence fundus camera and GC-1 pachymeter for comprehensive glaucoma evaluation.
On the other side of the Pacific, U.S.-based innovators are pushing the boundaries of corneal biomechanics and portable diagnostics. Reichert Technologies has strengthened its footprint with the Tono-Vera applanation tonometer and Ocular Response Analyzer, and its March 2025 introduction of wireless connectivity reflects a broader industry emphasis on data integration and remote workflow compatibility. Carelon Medical Technologies is pursuing a distinctly modern angle with the Phelcom Eyer portable fundus camera enhanced by AI for glaucoma detection, a configuration that aligns with decentralized screening and point-of-care trends.
European and transatlantic players continue to influence both clinical standards and home-monitoring adoption. Haag-Streit remains a reference point in visual field testing through its Octopus perimeters and AT 900 applanation tonometer, while Finland's iCare has carved a specialized niche in rebound tonometry with devices such as the iCare TA01i for clinic and home IOP monitoring. The clinical relevance of home-based monitoring was further validated in September 2024, when iCare presented HOME2 study results supporting self-monitoring use cases at a major ophthalmology conference.
What unites these players is not just product capability, but the race to embed diagnostics into longitudinal care pathways. As AI-enabled interpretation, connected devices, and patient-administered monitoring gain traction, competitive advantage will increasingly depend on how well manufacturers can align hardware performance with software intelligence, clinical evidence, and provider workflow integration.
Prostate Cancer Diagnostics Market
Market Dynamics: Regulation, Reimbursement, and the Adoption Equation
Growth in glaucoma diagnostics does not occur in a vacuum. The pace at which new devices reach the clinic, and the speed at which they are adopted, is heavily shaped by regulatory classification and reimbursement architecture. Our research situates these forces within the practical realities that procurement teams and clinical leaders navigate every day.
From a regulatory standpoint, device classification continues to influence time-to-market and development cost. In the United States, non-contact tonometers are classified as Class II devices subject to 510(k) premarket notification, a framework that directly affects product launch sequencing and competitive entry timing. At the same time, international performance standards such as ISO 8619:2019 continue to define expectations for Goldmann-type applanation tonometers, reinforcing the importance of compliance in procurement decisions.
Reimbursement realities are equally decisive. In the U.S., coding and coverage structures determine whether a diagnostic capability translates into sustainable clinical utilization. CPT code 92133, which covers confocal microscopy of the optic nerve for glaucoma, carried Medicare reimbursement averaging USD 35.62 in 2025, while visual field examination under CPT code 92081 is reimbursed at approximately USD 25 to USD 40 per eye under Medicare Part B. These reimbursement parameters influence not only which tests are prioritized in clinic, but also how providers evaluate the economic case for expanding diagnostic capacity.
Worldwide Glaucoma Diagnostics Market
Together, regulatory classification and reimbursement visibility create a layered adoption environment. Manufacturers that anticipate coding pathways, align device features with reimbursable indications, and provide robust clinical documentation will find a faster path to implementation. Conversely, promising technology that fails to fit cleanly into existing reimbursement and workflow structures can stall in pilot phases, regardless of its technical sophistication.
Why This Research Matters for 2026 Decision-Making
As organizations finalize their 2026 strategies, the glaucoma diagnostics market presents a rare combination of steady macro growth and rapid micro-level disruption. Total market expansion is being driven not only by demographic pressure and rising disease awareness, but also by the increasing sophistication of diagnostic tools that enable earlier detection and more consistent progression monitoring. Yet the real strategic question is not whether the market is growing, but where value will accrue within that growth.
This is precisely where PW Consulting's research adds differentiated value. Our study maps the interplay between technology adoption, competitive maneuvering, end-user procurement behavior, and the regulatory and reimbursement environment that conditions commercial success. It is designed to help leadership teams answer practical questions: Which diagnostic modalities are gaining clinical traction? Where are procurement budgets likely to shift over the forecast period? How are leading competitors using product launches, software updates, and clinical validation to reinforce their positions? And how should an organization position itself to capture share without overcommitting to immature segments?
The answers to these questions cannot be reduced to a single headline figure. They require a structured reading of market architecture, where segmentation, geographic variation, and end-user dynamics intersect with product innovation cycles. That is the depth our analysis provides, and why it serves as a strategic companion for planning, investment, and competitive positioning.
Access the Full Intelligence: The Report Your 2026 Strategy Needs
The Worldwide Glaucoma Diagnostics Market report is more than a forecast table. It is a comprehensive decision-support instrument built to inform product strategy, market prioritization, competitive benchmarking, and investment planning across the 2026 to 2032 horizon. Readers who engage with the full study gain access to the segmentation detail, regional context, end-user breakdown, and competitive profiling needed to translate market momentum into executable strategy.
To explore the complete analysis, including the detailed segmentation views, market concentration insights, company profiles, and the latest regulatory and reimbursement context, visit the PW Consulting source page for the full Worldwide Glaucoma Diagnostics Market research. The report is structured to give your team the clarity required to move from awareness to action, with the kind of granular intelligence that supports confident decisions in a market where precision matters.
For detailed analysis of this topic, please visit the official page: Worldwide Glaucoma Diagnostics Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Used Telehandlers Hit $3.19B in 2025, Set for 5.81% CAGR Through 2032
By pmarketresearch, 2026-09-16
Strategic Intelligence for the 2026 Fleet Planner: Why the Used and Refurbished Telehandler Market Demands a Disciplined Playbook
The global market for used and refurbished telehandlers has evolved from a peripheral cost-saving alternative into a strategically managed segment that shapes fleet composition, total cost of ownership, and operational resilience across construction, agriculture, and industrial logistics. As procurement teams recalibrate capital allocation for 2026, the interaction between tightening equipment availability, evolving compliance expectations, and shifting material costs has turned second-hand and reconditioned telehandlers into a decisive lever for margin protection and service continuity. A focused, data-grounded assessment of this landscape is no longer optional; it is the foundation for credible fleet strategy, pricing discipline, and competitive positioning.
Drawing on PW Consulting’s newly released analysis, this intelligence briefing previews the scope of our worldwide market study and explains how decision-makers can translate forward-looking research into defensible 2026 operating plans. The objective is not to publish every figure in open view. Instead, we aim to demonstrate analytical rigor, clarify the mechanics behind value migration, and show precisely where deeper segmentation, benchmarking, and scenario planning will pay dividends for executives who need to act with precision.
Macro Trajectory and the Strategic Signal for 2026 Decision-Making
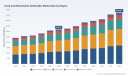
The measured trajectory of this segment over the past five years underscores a structural rebalancing rather than a cyclical rebound. Historical performance from 2020 through 2025 reveals a market that expanded from approximately $2,405.6 million to $3,185.5 million, reflecting sustained demand for cost-efficient material handling equipment alongside persistent pressure on new-unit affordability. This progression did more than lift volumes; it reshaped buyer behavior, dealer inventory strategy, and the economics of certified refurbishment programs across multiple regions and end-use verticals.
Looking ahead, the forecast horizon of 2026 to 2032 indicates continued expansion at a CAGR of 5.81%, with revenue projected to advance through the mid-$3,200 million range in 2026 and progressively toward the $4,730 million zone by the end of the outlook period. These directional signals carry immediate implications for 2026 planning. First, they suggest that demand is not merely returning to pre-disruption levels but is consolidating around more sophisticated procurement models, including certified pre-owned programs, structured maintenance warranties, and rental-integrated access strategies. Second, the pace of growth implies that pricing power, inventory positioning, and service quality will increasingly differentiate participants who can meet compliance and uptime expectations at scale.
For executives, the core strategic takeaway is that the used and refurbished telehandler category is becoming more professionalized and more closely tied to operational outcomes than in prior cycles. As capital expenditure constraints persist, contractors and agribusiness operators are looking for equipment that delivers predictable performance without locking balance sheets into long-lived asset commitments. That trend elevates the importance of accurate market sizing, demand decomposition, and region-specific dynamics—precisely the kinds of insights our full study is designed to provide.
Telehandlers Market
What the Study Covers Beyond Top-Line Figures
A credible strategy requires more than a headline growth rate. Our research is built to give operators, OEMs, dealers, and investors a practical map of where value is created and where risks concentrate. Rather than stopping at aggregate market size, the study unpacks the structural drivers, competitive behaviors, and operational variables that determine whether a 2026 plan is resilient or fragile.
The analysis is organized to support real-world decisions across multiple layers of the business:
- Demand composition across telehandler categories, with attention to how high-reach, compact, and heavy-lift configurations align with different job-site requirements, fleet mixes, and refurbishment economics.
- Application-level segmentation that connects equipment utilization patterns to construction, agriculture, and industrial/logistics workflows, helping readers understand where refurbished inventory flows and why certain verticals absorb supply faster.
- Regional evaluation that places market opportunity in the context of trade flows, dealer network maturity, regulatory environments, and localized procurement culture, without reducing the picture to simplistic rankings.
- Competitive positioning across established manufacturers with active certified-used and refurbished channels, including how OEM-backed programs influence residual value perception, warranty confidence, and customer switching behavior.
- Operational cost factors and supply-side pressures, particularly the interplay between steel input dynamics, component sourcing, and pricing behavior in the refurbished value chain.
- Regulatory and compliance considerations that affect operator certification, inspection standards, documentation requirements, and the commercial attractiveness of used equipment relative to new.
In addition to structural segmentation, the report incorporates scenario-ready context that reflects the external forces shaping 2026 execution. Material cost behavior is examined with attention to how structural inputs influence manufacturing economics and, by extension, the cost floor for both new and refurbished units. Trade-policy signals and tariff developments are assessed for their potential to alter import costs and dealer margin structures. Compliance shifts are mapped to practical operational consequences, especially where increased emphasis on operator certification and digital documentation can raise the attractiveness of well-documented used equipment. The study also addresses the strategic reorientation toward rental and access-based models, which has become a defining feature of how contractors maintain flexibility while managing balance-sheet exposure.
This breadth is intentional. Used and refurbished equipment cannot be understood through a single lens. A dealer may see strong demand in one vertical while facing inventory compression in another. A manufacturer may gain from certified program perception in one geography while confronting cost and compliance headwinds elsewhere. Our framework is designed to help readers interpret those tensions rather than force them into a single narrative.
Competitive Landscape and the Realities of OEM-Backed Refurbishment
The competitive architecture of the used and refurbished telehandler market is defined by the presence of major manufacturers whose new-equipment brands carry spillover advantages into the secondary market. Companies such as JCB, Caterpillar Inc., Manitou Group, JLG Industries, Merlo S.p.A., Dieci S.r.l., Terex Corporation through its Genie brand, Bobcat Company, Liebherr Group, CNH Industrial, Wacker Neuson SE, Haulotte Group, and Claas KGaA mbH each hold distinctive positions shaped by product range, dealer reach, application focus, and certification practices.
One recurring theme is the strategic value of OEM-recognized refurbishment. Caterpillar’s used telehandler programs, for instance, illustrate how inspected and reconditioned models can be channeled through authorized dealer networks with a heavy-duty orientation toward construction and material handling. Manitou’s dedicated used and refurbished inventory across MT and MLA series demonstrates a multi-vertical approach spanning construction, agriculture, and industrial applications. JLG’s used and refurbished options, supported by rental fleets and dealer networks, show how rotating and compact models can broaden access in North American and international markets. Merlo emphasizes rotating telehandler performance with refurbished programs aimed at high-performance construction and agriculture use, while Dieci addresses agriculture and construction demand with compact and heavy-lift options. Bobcat’s certified used programs reflect a compact construction and landscaping orientation, and Liebherr’s dealer-network-based refurbished offerings reinforce a premium heavy-equipment positioning across construction and mining applications.
Beyond manufacturer programs, the competitive environment is shaped by a broader ecosystem of brands with integrated agricultural and material-handling identities. CNH Industrial’s New Holland telehandlers support agriculture and construction through active used equipment sales, while Claas aligns telehandler offerings with broader agricultural equipment portfolios and provides used and refurbished options for farm and light construction use. Wacker Neuson emphasizes compact models for construction and municipal applications, Haulotte supports aerial and material handling needs in construction, and JCB extends its global dealer networks and certified programs into both construction and agriculture. Terex Corporation’s Genie GTH line adds construction and industrial material handling coverage through global sales channels.
What distinguishes the stronger participants is not merely the presence of a used channel, but the consistency with which certification, inspection rigor, warranty structure, and documentation reduce perceived risk for buyers. In a market where residual value confidence and uptime expectations matter as much as headline price, OEM-backed programs can shape purchasing decisions, resale dynamics, and dealer inventory strategy. At the same time, the presence of many capable competitors means that differentiation now depends on operational execution: refurbishment turnaround, parts availability, regional coverage, and the ability to match equipment condition to specific application demands.
Recent industry activity reinforces this competitive intensity. At ConExpo 2026 in January 2026, multiple manufacturers including JLG, Caterpillar, and Manitou showcased telehandler innovations centered on smarter controls, enhanced stability systems, and efficiency features. These product signals matter for the used and refurbished market because they establish the performance baseline that buyers compare against second-hand alternatives. As jobsite material handling technology advances, the relative appeal of refurbished units will increasingly depend on whether they can meet evolving control, safety, and productivity expectations without compromising affordability.
Demand Drivers, Regulatory Pressure, and the Cost Structure Debate
The strategic story of 2026 is incomplete without the operating context that surrounds equipment acquisition and deployment. Several external forces are converging to influence how buyers evaluate used and refurbished telehandlers and how suppliers structure offers.
A dominant trend is the continued expansion of rental and flexible access models for used and refurbished equipment. Contractors and project teams are seeking ways to reduce capital expenditure while maintaining flexibility in infrastructure and construction work. That posture increases the relevance of refurbished units that can be accessed through short-term or project-based arrangements, while also pushing manufacturers and dealers to think beyond outright sale toward service-integrated supply. In practical terms, this means that fleet planners must evaluate not only acquisition price but also availability, maintenance support, and the operational fit of equipment across intermittent deployment cycles.
On the regulatory side, OSHA updates for 2025 place greater emphasis on operator certification, digital documentation, and compliance for heavy equipment, including telehandlers classified as rough-terrain forklifts. The resulting focus on training and inspections can raise the operational value of used equipment that comes with clearer records, documented condition, and verified refurbishment standards. Conversely, equipment with incomplete documentation or uncertain maintenance history may face greater scrutiny, which can widen the perceived gap between certified and uncertified supply.
Trade and material dynamics add another layer of complexity. The increase in U.S. Section 232 steel tariffs to 50% effective June 2025, with certain exceptions, has contributed to higher costs for imported steel components used in construction equipment including telehandlers. That pressure interacts with the broader cost structure of steel manufacturing, where raw materials account for a substantial share of expenses and scrap metal serves as a primary input for electric arc furnace production used in heavy equipment components. At the same time, steel pricing in the U.S. Midwest has shown a pattern of stabilization in the low-to-mid $800s per short ton in mid-2025, with expectations of range-bound to modestly firmer pricing into early 2026 driven by construction demand.
These inputs matter because they influence the cost floor beneath both new and refurbished equipment. For buyers, the implication is that the price differential between new and used units may not behave linearly over time. For sellers and refurbishers, the implication is that component costs, parts availability, and regional sourcing strategies will shape margin sustainability. A market research approach that ignores these cost-side forces risks misreading competitive pricing behavior and inventory strategy.
Why This Study Matters for 2026 Strategy
The central challenge for 2026 is not simply whether the used and refurbished telehandler market is growing, but how growth is distributed across configurations, applications, and regions, and what that distribution means for pricing, inventory, and competitive positioning. Aggregate momentum is useful as a signal, but it is insufficient as a decision instrument. Executives need to know where demand concentrates, which segments show stronger resale resilience, how OEM refurbishment programs influence buyer trust, and where regulatory or cost pressures may alter the economics of acquisition and resale.
Worldwide Used and Refurbished Telehandler Market
The report we have prepared is designed to bridge that gap between directional awareness and execution-ready intelligence. It provides a structured reading of market size progression, forward outlook, segmentation logic, and competitive behavior, while preserving enough granularity for operational use. Critically, it also situates the numbers within the operating environment: rental-led demand models, certification and compliance expectations, steel and component cost pressures, tariff exposure, and product innovation that raises the performance bar for used equipment.
Firms that act on this intelligence can make better decisions about inventory mix, regional expansion, certified program investment, pricing strategy, and partnership selection with dealer and rental networks. Procurement teams can use the same evidence base to time acquisitions more effectively, assess total cost of ownership with greater confidence, and reduce exposure to undocumented or unreliable equipment. Investors and analysts can use the market structure and concentration context to evaluate where competitive advantage is being built and where consolidation risk may emerge.
Where Deeper Intelligence Will Pay Off
Our Worldwide Used and Refurbished Telehandler Market study is intended to serve as the reference point for precisely these decisions. It combines historical grounding, a 2026 to 2032 outlook, segmentation analysis, competitive profiling, and external market context in a single framework. By design, the public-facing preview conveys the strategic logic and the analytical discipline behind the work, while the full report delivers the segmented figures, benchmarking detail, and regional and application-level granularity needed to convert insight into action.
For organizations planning 2026 capital deployment, fleet composition, dealer strategy, or product program investment, the value of this research lies in its ability to turn a complex, fast-moving segment into a structured decision basis. The next step is to examine the full intelligence package, where segmentation, competitive detail, and scenario context are presented with the specificity required for confident execution.
For detailed analysis of this topic, please visit the official page: Worldwide Used and Refurbished Telehandler Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Active Optical Cable Market Hits $4.5B in 2025, Projected 18% CAGR to 2032
By pmarketresearch, 2026-09-16
The Optical Backbone of the AI Era: Strategic Intelligence for the Active Optical Cable and Extender Market Through 2032
As enterprises architect the next generation of data infrastructure, the physical layer is no longer a commodity afterthought—it is a strategic bottleneck and a competitive lever. The Worldwide Active Optical Cable and Extender Market research from PW Consulting delivers a structured, forward-looking intelligence framework designed to help technology leaders, procurement directors, and corporate strategists navigate one of the most consequential connectivity shifts in recent memory. Drawing on historical tracking from 2020 through 2025 and a comprehensive forecast window extending to 2032, this study maps how active 광학 connectivity is evolving alongside AI workloads, hyperscale expansion, and tightening edge deployments.
Why 2026 Is a Defining Year for Optical Interconnects
The global market for active optical cables and optical extenders crossed the $4.5 billion threshold in 2025 and is projected to exceed $5.49 billion in 2026, continuing a trajectory that pushes the market well beyond $14.3 billion by 2032. This sustained expansion reflects a compound annual growth rate of roughly 18 percent, a pace that outstrips broader connectivity markets and signals a fundamental rewiring of infrastructure demand. The acceleration is not merely cyclical. It is structural, driven by the convergence of higher-speed interface requirements, longer rack-to-rack reach needs in high-density environments, and the ongoing migration of compute and storage architectures toward optics-based signaling.
For decision-makers planning capital allocation, vendor partnerships, and product roadmaps in 2026, this market profile matters because supplier capacity, pricing behavior, and technology transitions are reshaping the cost and performance assumptions that teams once relied on. The report translates that complexity into a decision-ready format, enabling leaders to benchmark their internal assumptions against a rigorously modeled market baseline and to identify where timing, positioning, and sourcing flexibility will create durable advantage.
What the Study Covers: From Macro Trajectory to Tactical Playbooks
This market research is built for practitioners who need more than headline numbers. It begins with a detailed sizing and forecast model, anchoring historical revenue from 2020 through 2025 and projecting market movement through 2032 in U.S. dollars. The model is structured so that leadership teams can assess momentum across different adoption drivers without losing sight of the market’s overall direction. Alongside the top-down expansion narrative, the report provides a granular breakdown of how demand is spreading across major geographic markets and how the product landscape is divided between active optical cables and optical extenders.
Worldwide Active Optical Cable and Extender Market
The segmentation analysis is paired with end-use mapping that highlights where connectivity demand is intensifying. Rather than treating applications as static categories, the study examines how each segment is being reshaped by hardware refresh cycles, performance ceilings on legacy copper-based solutions, and the push toward higher-density interconnects in mission-critical environments. This approach gives readers a practical way to evaluate where their own product portfolios, distribution channels, or procurement requirements intersect with the largest points of market pressure.
To support operational planning, the report also examines the cost structure and dynamics that influence purchasing and engineering decisions. One of the more consequential findings is the composition of the total bill of materials: transceiver chipsets account for approximately 65 percent of the total cost in active optical cables, while fiber cable itself represents less than 10 percent. That cost concentration has direct implications for pricing negotiations, design choices, and supply risk. The study further explores the ongoing annual price erosion seen in standard 100G active optical cable units, along with the substantial price difference that can exist between OEM-coded configurations and compatible white-box alternatives. These dynamics do not simply affect unit economics; they shape how organizations should structure vendor relationships, validation processes, and inventory strategies.
Competitive Landscape: Who Shapes the Market and How
The active optical cable and extender market is not a fragmented commodity space. It is a concentrated, technically demanding arena in which a relatively small group of manufacturers exerts meaningful influence over innovation cadence, availability, and pricing norms. The report profiles the companies most relevant to enterprise, data center, telecom, and industrial buyers, offering comparative insight into positioning, product emphasis, and strategic intent.
Among the leaders, Corning Incorporated continues to push active optical cable innovation beyond conventional interconnect thinking. Its recent showcase at OFC 2026 highlighted AI-focused developments, including multicore fiber solutions intended to support higher density, the Contour Flow micro cable for data center interconnects, and co-packaged optics systems. This direction signals how incumbent materials and fiber specialists are expanding into the architecture-level decisions that surround cable deployment, especially where space, thermal management, and density constraints are becoming critical.
Molex LLC remains a strong presence in active optical cable portfolios aimed at high-speed data centers, high-performance computing, and storage environments. Its value proposition centers on the practical advantages of optical cable assemblies over traditional modular approaches, with emphasis on cost efficiency, low power consumption, and installation simplicity. For system integrators and facility operators, such positioning matters because it ties product design directly to deployment realities rather than pure performance specifications.
Amphenol Communications Solutions contributes rugged, reliability-oriented active optical cable solutions suited for industrial, data center, and high-density settings, including applications that extend into military and aerospace as well as enterprise networking. Broadcom Inc. supports the market from the integrated connectivity side, supplying active optical cables and components that address hyperscale data centers, high-performance computing, and Ethernet and PCIe-based applications. Coherent Corp., with its heritage in advanced fiber optic transceivers and high-speed interconnects, continues to align its portfolio with the growing demand for 400G and 800G-rate connectivity across data centers, telecommunications, and fast interconnect applications.
TE Connectivity rounds out a major tier of global suppliers with active optical cable assemblies and connectivity solutions serving data centers, telecommunications, and industrial markets. Sumitomo Electric Industries Ltd. and Fujikura Ltd. extend the competitive field with high-speed, low-loss cable solutions designed for enterprise, data center, and telecom infrastructure, reinforcing the importance of fiber-quality and cable-performance engineering in long-term reliability. 3M Company and Siemon further broaden the supplier base, with active optical cable offerings that support enterprise networking and data center environments where standardized, dependable connectivity is essential.
On the Asia-based supply side, a distinct set of manufacturers has built momentum around cost-effective active optical cable production for data center and telecom applications. Shenzhen Gigalight Technology Co., Ltd. is noted for SFP+, QSFP, and higher-speed variants; EverPro Technology Co., Ltd. specializes in SFP+ and QSFP series for high-speed transmission; T&S Communication Co., Ltd. produces active optical cables and related fiber optic components for global markets; and Shenzhen Sopto Technology Co., Ltd. offers a range of active optical cables for networking and data transmission use. These companies are important to the market because they shape price competition, alternative sourcing paths, and the availability of compatible solutions in volume-driven segments.
Fiber Optic Cables Market
Recent developments underscore how quickly the technology frontier is moving. In March 2026, Corning Incorporated used its OFC presence to spotlight AI-oriented fiber and interconnect innovations, including multicore fiber for greater density and Contour Flow micro cable for data center interconnects, alongside co-packaged optics systems. Around the same time, MediaTek announced progress in microLED-based active optical cable technology and later described collaboration with Microsoft Research on miniaturized MicroLED light sources aimed at improving data center efficiency and AI infrastructure. This wave of innovation suggests that the market’s next performance leap may be as much about light-source design, packaging, and density as about cable geometry alone.
Market Dynamics and Structural Risks Decision-Makers Can’t Ignore
The 18 percent growth trajectory is compelling, but growth does not erase friction. One of the most important structural risks in the active optical cable market is component availability. Critical optoelectronic parts such as VCSEL lasers and photodetectors continue to face long lead times and limited manufacturing capacity. In practice, this means some active optical cable configurations can experience delivery timelines stretching to six or eight months. For organizations designing systems around tight build schedules or large-scale rollouts, this supply constraint can turn a seemingly straightforward interconnect choice into a project-level exposure.
Pricing pressure adds another layer of complexity. Standard 100G active optical cable units continue to experience annual price erosion in the range of 12 to 15 percent, a trend that rewards buyers who can plan volume, timing, and specification carefully but also compresses margins for suppliers who cannot differentiate on performance, integration, or support. The price delta between OEM-coded and compatible white-box options can be several times higher, which makes specification control, validation rigor, and supply-chain transparency essential for enterprises trying to balance cost against reliability.
Tariff and trade developments introduce further uncertainty. Increases in tariffs on imported construction and electronic materials can raise project costs and complicate procurement when active optical cable components are part of a broader supply chain. For multinational deployments or multi-tier sourcing strategies, the cost impact of trade policy can be as influential as technology selection itself. These dynamics are not peripheral footnotes. They affect sourcing footprints, inventory buffers, and the financial model behind large-scale infrastructure commitments.
What Strategic Buyers Gain From This Research
The study is designed to support several core decision contexts. For technology and infrastructure leaders, it provides a consolidated view of where the market is heading and which segments are likely to drive the most significant demand shifts. For procurement and supply-chain teams, it frames the trade-offs between performance, delivery risk, and cost in a way that supports more resilient sourcing strategies. For product and business developers, it offers a competitive map that highlights where incumbents, specialists, and Asia-based manufacturers are concentrating their efforts, and how recent technology announcements may reshape expectations over the next planning cycle.
Because the report integrates historical performance, forward forecasts, segmentation insight, and competitive context in one framework, it helps organizations align internal assumptions around a common intelligence baseline. That is particularly valuable in a market characterized by rapid speed-class transitions, uneven component availability, and strong differences in total cost of ownership depending on configuration and sourcing choices. Rather than forcing teams to reconcile fragmented signals, the study provides a focused reference point for evaluating opportunity, risk, and timing.
Looking Ahead: Where to Focus in 2026 and Beyond
The most important takeaway for 2026 is that active optical cables and optical extenders are becoming strategic enablers of compute density, AI infrastructure, and high-speed interconnect design, not just passive transmission media. Demand is being pulled by data centers and cloud computing, accelerated by high-performance computing, and extended by consumer electronics, pro-AV and digital signage, and medical and industrial imaging applications. At the same time, supply-side realities—chipset cost concentration, laser and detector availability, pricing erosion, and trade exposure—are shaping how that demand translates into real-world purchasing and deployment decisions.
For leaders who need to move from high-level awareness to actionable planning, the full report provides the detailed breakdown, scenario-ready segmentation, and company-specific intelligence necessary to support confident decisions. The complete market sizing, regional and application-level analysis, competitive profiles, and forward forecasts are available through the source page, where the full depth of the study can be reviewed in context. In a market expanding at this pace, the difference between reactive purchasing and strategically informed positioning often comes down to the quality of the intelligence underneath the decision. This research is built to provide exactly that.
For detailed analysis of this topic, please visit the official page: Worldwide Active Optical Cable and Extender Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Fleet Maintenance Market to Hit $358.1B by 2032, 5.11% CAGR
By pmarketresearch, 2026-09-16
Navigating the Future of Fleet Maintenance: Strategic Insights for 2026 and Beyond
The global fleet maintenance service market is undergoing a profound transformation, driven by the convergence of advanced telematics, artificial intelligence, and evolving regulatory frameworks. As organizations strive to optimize operational efficiency while managing escalating costs, understanding the trajectory of this sector is no longer optional—it is a strategic imperative. This analysis draws upon comprehensive market research to illuminate the current landscape and forecast the critical trends shaping decision-making through 2032.
Market Trajectory and Growth Dynamics
The worldwide fleet maintenance service market has demonstrated consistent expansion over the past half-decade, reflecting the essential nature of vehicle upkeep in commercial and institutional logistics. Historical data from 2020 through 2025 indicates a steady upward climb in revenue, culminating in a base market size of approximately 252,480 million USD in 2025. This growth trajectory is projected to accelerate moderately through the forecast period ending in 2032, with a Compound Annual Growth Rate (CAGR) of 5.11 percent.
By 2032, the market is expected to reach a valuation exceeding 358,000 million USD. This expansion is not merely a function of inflationary adjustments but represents a fundamental increase in demand for sophisticated maintenance solutions. The mid-2020s, specifically 2026, stand as a pivotal inflection point where the adoption of predictive technologies begins to meaningfully offset traditional reactive models. For enterprise strategists, this signals a shifting value proposition where uptime assurance and lifecycle cost management become the primary drivers of procurement decisions.
Segmentation Shifts and Operational Priorities
The composition of spending within the fleet maintenance ecosystem is diversifying. Revenue generation is distributed across various service types, vehicle categories, and geographic regions, each presenting unique opportunities and challenges for stakeholders. Preventive maintenance continues to command a significant share of the market, underscoring the industry's commitment to scheduled upkeep as a means of avoiding catastrophic failures. However, the rise of predictive maintenance services is gaining momentum, reflecting a broader industry shift toward data-driven decision-making capabilities.
In terms of vehicle types, light commercial vehicles and heavy commercial vehicles represent the dominant segments, reflecting the critical role of logistics and supply chain operations in the global economy. Passenger cars also contribute substantially, particularly within corporate fleets and ride-sharing ecosystems. Geographically, the market is well-distributed, with significant activity across North America, Europe, and the Asia Pacific region. Each region presents distinct regulatory and operational environments that influence how maintenance services are procured and delivered.
It is important for decision-makers to recognize that these segments are not static. As vehicle technology evolves, particularly with the integration of electric powertrains and connected systems, the nature of required maintenance services is changing. Companies that align their service strategies with these segment-specific nuances will be better positioned to capture value in the coming years.
Technology Integration and AI Advancement
Technology is the primary catalyst for efficiency gains in the fleet maintenance sector. The integration of cloud-based platforms, telematics, and artificial intelligence is redefining how maintenance workflows are managed. Modern platforms now offer comprehensive tracking of work orders, inspections, and repair approvals, enabling fleet managers to maintain visibility over asset health without relying on manual processes.
AI-driven service advisors are emerging as a key differentiator, capable of accelerating high-volume repair approvals and simplifying complex maintenance decision-making. These tools analyze vast amounts of vehicle data to recommend actions, prioritize tasks, and control costs. Furthermore, the deployment of AI-powered dashcams and 360-degree visibility solutions is providing real-time safety insights that directly support maintenance decisions. By identifying potential issues before they lead to breakdowns, these technologies help reduce downtime and enhance overall fleet maintenance efficiency.
The move toward unified ecosystems is also notable. Recent developments have seen the launch of platforms that integrate vehicle claims, repairs, and fleet management data into a single interface. This consolidation allows for a more holistic view of fleet health and streamlines the interaction between maintenance providers and fleet operators. For organizations evaluating technology vendors, the ability of a solution to integrate seamlessly with existing infrastructure and provide actionable analytics is a critical selection criterion.
Competitive Landscape and Vendor Dynamics
The competitive environment in the fleet maintenance service market is characterized by a mix of specialized technology providers, large telematics firms, and full-service fleet management companies. The market remains relatively fragmented, with top competitors holding a combined share that suggests ample room for consolidation or niche specialization.
Leading technology firms are focusing on enhancing their software capabilities to offer deeper insights and automation. Companies such as Fleetio, Geotab, Verizon Connect, Samsara, and Trimble are at the forefront of providing cloud-based fleet management platforms, open-platform solutions, and transportation management systems. These vendors emphasize advanced analytics, predictive maintenance, diagnostics, and marketplace integrations to support fleet maintenance optimization and compliance.
Simultaneously, traditional fleet management and leasing companies continue to play a vital role, particularly for large organizations seeking end-to-end solutions. Entities like Ryder System Inc., Penske Truck Leasing, Element Fleet Management, ARI Fleet Management, and Wheels Inc. offer comprehensive vehicle upkeep services, often combining leasing with on-site repairs and dedicated maintenance programs. Their value proposition often centers on cost control, lifecycle management, and the ability to handle large-scale fleet operations.
Worldwide Fleet Maintenance Service Market
Service providers specializing in mobile and on-site maintenance, such as FleetNet America, Dickinson Fleet Services, and Wrench Inc., are also gaining traction by offering convenience and digital management tools. These companies address the need for flexible repair options that minimize vehicle downtime. The presence of diverse player types ensures that fleets of varying sizes and operational complexities can find solutions tailored to their specific needs.
Regulatory and Economic Pressures
External factors are exerting significant pressure on fleet maintenance strategies. Labor costs have become a critical concern, with skilled technician shortages and inflation driving up maintenance rates. Recent sector analysis suggests that repair costs have increased by up to 20 percent in recent periods, compelling fleets to implement higher pay scales and adopt technology tools to address turnover and sustain service levels. This labor dynamic necessitates a strategic focus on efficiency and automation to mitigate cost impacts.
Regulatory compliance is another major driver of change. New enforcement standards and inspection requirements are being introduced to enhance safety and environmental performance. For instance, updates to inspection protocols in California have adjusted requirements for vehicles under specific weight thresholds, aligning some standards with federal annual mandates while maintaining stricter oversight for heavier vehicles. Additionally, changes by the Federal Motor Carrier Safety Administration (FMCSA) include overhauls to compliance measurement systems, splitting vehicle maintenance violations into separate categories. These changes directly impact work order speed and completeness for pre-trip defects, requiring fleets to adapt their maintenance workflows to ensure compliance.
Environmental regulations are also influencing maintenance practices. Programs such as the Clean Truck Check in California impose annual fees and associated costs for emissions-related compliance. These mandates add to the total cost of ownership and require fleets to maintain rigorous records and performance standards to avoid penalties. Navigating this complex regulatory landscape requires robust management systems capable of tracking compliance status and scheduling necessary interventions.
Worldwide Heavy Equipment Maintenance Service Market
Strategic Recommendations for 2026 Decision-Makers
As organizations plan their strategies for 2026 and the subsequent forecast period, several key actions emerge as priorities. First, investing in predictive and preventive maintenance technologies should be a core component of operational planning. The ability to anticipate failures and schedule repairs proactively offers a clear return on investment through reduced downtime and extended asset life.
Second, managing labor constraints requires a dual approach. While competitive compensation is necessary to attract and retain skilled technicians, leveraging technology to streamline workflows and reduce manual effort can alleviate pressure on existing staff. Tools that automate scheduling, tracking, and reporting allow technicians to focus on high-value repair activities.
Third, compliance readiness must be integrated into maintenance planning. With evolving regulations regarding vehicle inspections and emissions, fleets need systems that can adapt quickly to new requirements. Ensuring that maintenance programs are aligned with regulatory standards will minimize risk and avoid costly penalties.
Finally, vendor selection should be guided by a clear understanding of long-term needs. The market offers a wide range of solutions, from specialized software platforms to full-service management contracts. Evaluating vendors based on their ability to integrate, scale, and provide actionable insights will ensure that partnerships contribute to sustained operational excellence.
Conclusion
The worldwide fleet maintenance service market is poised for continued growth, fueled by technological innovation and the enduring need for reliable vehicle operations. For leaders navigating this landscape, the insights provided in the detailed market research offer a roadmap for strategic action. By understanding the underlying dynamics of market size, segmentation, competition, and regulation, organizations can make informed decisions that drive efficiency and resilience. Access to the full intelligence suite will provide the granular data necessary to refine these strategies further, ensuring that fleets remain competitive in an increasingly complex environment.
For detailed analysis of this topic, please visit the official page: Worldwide Fleet Maintenance Service Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global High Purity Lignin Market to Reach $69.18M by 2032, 7.21% CAGR
By pmarketresearch, 2026-09-16
Global High Purity Lignin Market Outlook: Strategic Intelligence for the 2026 Business Cycle
The transition from fossil-based feedstocks to renewable biopolymers represents one of the most significant structural shifts in the global chemicals and materials landscape. As we move through 2026, high purity lignin has emerged as a critical enabler of this transition, offering viable pathways for decarbonization across adhesives, composites, carbon materials, and specialty chemicals. Our latest Worldwide High Purity Lignin Market research provides decision-makers with a rigorous, forward-looking intelligence framework designed to navigate capacity deployment, competitive positioning, and application commercialization over the 2026 to 2032 horizon.
For executives, investors, and strategy teams, the imperative is clear: market timing, technology selection, and partnership strategy will dictate who captures value in a rapidly maturing bio-based supply chain. This report delivers the granular market architecture, technology roadmaps, and competitive scaffolding required to make those decisions with confidence.
Market Trajectory and Growth Architecture
The global high purity lignin market has demonstrated sustained expansion over the past half-decade, driven by accelerating substitution demand, regulatory tailwinds, and scale-up activity across pulp-integrated and standalone biorefinery operations. Historical performance from 2020 through 2025 reflects a consistent upward trajectory, with total market revenue climbing from approximately 31.25 million USD to 42.5 million USD. The base year of 2025 anchors a forecast period that extends through 2032, during which the market is projected to expand at a compound annual growth rate of 7.21 percent.
This growth profile is not merely a function of volume scaling; it reflects a structural revaluation of lignin from a low-value pulp byproduct to a high-value, specification-driven biopolymer. Forecast trajectories through 2032 indicate continued appreciation, with revenue levels expected to surpass 69 million USD by the close of the forecast window. The compounding nature of this expansion underscores the importance of early-mover positioning, capacity alignment, and application-specific qualification timelines that can span multiple years in regulated end markets.
Several macro forces are reinforcing this trajectory. Stringent carbon policies and circular-economy mandates across Europe are accelerating lignin valorization through bioeconomy funding mechanisms and green public procurement frameworks. Simultaneously, regulatory pressure on traditional chemical inputs, including chrome restrictions in drilling fluids and expanding disclosure requirements on embodied carbon, is driving end-users to qualify lignin-based alternatives in construction and oilfield service applications. These demand-side catalysts are interacting with supply-side developments in separation technology, purification capability, and integrated mill economics to reshape the competitive landscape.
Segmentation Logic and Application Pathways
Understanding the market requires a clear grasp of how value is distributed across type, application, and geography. The report dissects the high purity lignin landscape across multiple segmentation dimensions, mapping revenue contribution, growth intensity, and adoption dynamics for each node without exposing the precise percentage splits that drive commercial negotiation leverage.
Lignin Type Landscape
The market encompasses distinct lignin categories, each with unique processing routes, purity profiles, and end-market suitability. Organosolv-derived lignin dominates value contribution, reflecting its broader compatibility with higher-specification applications and its alignment with specialty chemical and polymer formulation requirements. Kraft lignin represents the second major value pillar, benefiting from established black-liquor recovery infrastructure, large-scale global availability, and growing deployment in resin, composite, and carbon material pathways. Soda lignin occupies a smaller but strategically relevant position, serving niche formulation needs where specific solubility or reactivity characteristics are required.
Global production capacity dynamics further shape type-level competition. Kraft lignin availability has expanded substantially, with global production capacity reaching significant kiloton thresholds by 2023, reinforcing its role as a foundational feedstock for scale-driven substitution. Yet high purity requirements, consistency standards, and downstream qualification processes mean that capacity alone does not translate directly into market share. Purification capability, lot-to-lot consistency, and technical service support increasingly determine commercial outcomes.
Application End-Use Dynamics
Demand is distributed across several high-growth application clusters, each with distinct qualification timelines, performance thresholds, and substitution economics. Resins and adhesives represent the largest application value pool, leveraging lignin as a renewable phenolic substitute and performance binder in engineered formulations. Carbon fiber and carbon material applications constitute a high-value secondary cluster, where lignin-derived precursors offer cost and sustainability advantages relative to conventional PAN-based routes, particularly as hard carbon and anode material development expands into next-generation battery chemistries. Bioplastics and polymer compounds form a growing segment, supported by patented transformation technologies that convert lignin into renewable thermoplastic and biomaterial grades. Specialty chemicals round out the application matrix, encompassing dispersants, binders, and functional additives where lignin's molecular architecture provides differentiated performance.
Geographic Distribution
Regional revenue distribution reflects the interplay of regulatory intensity, pulp and paper infrastructure density, and end-market demand maturity. Europe leads in value contribution, supported by ambitious bioeconomy policy frameworks, strong circular-economy procurement signals, and a dense concentration of technology developers and integrated producers. North America follows as a substantial value center, anchored by large-scale pulp operations, expanding lignin recovery investments, and growing qualification activity in construction, composites, and industrial applications. Asia Pacific and the Rest of World regions contribute incrementally but are gaining momentum as regional substitution demand, local formulation capabilities, and import-dependent supply chains evolve.
The report provides a complete geographic breakdown with market sizing, growth rates, and regional competitive mapping, but withholds granular regional percentage splits in this preview to preserve the analytical edge of the full dataset. Decision-makers requiring precise regional revenue allocations, localized demand forecasts, and country-level policy impact assessments will find those details within the complete report.
Competitive Landscape and Strategic Positioning
Market concentration is moderate, with the top three firms collectively capturing a significant share of total revenue and the top five firms extending that footprint further. This concentration profile signals a market in which scale, technology differentiation, and integrated supply relationships matter, but where specialized niche players and regional participants can still build defensible positions through purity, formulation expertise, and application-specific service models.
The competitive set includes globally established pulp-integrated producers, specialized lignin refiners, and technology-driven biomaterials developers. Borregaard brings over nine decades of experience in lignin-based biopolymers and lignosulfonates, delivering tailor-made high-purity solutions spanning dispersants, binders, and renewable alternatives to fossil chemicals. Stora Enso operates as the largest kraft lignin producer, leveraging its Lineo family of high-purity kraft lignin grades and NeoLigno binders for adhesives, composites, and carbon materials through its LignoBoost technology platform. UPM Biochemicals emphasizes consistent quality and formulation support for sustainable applications across resins, adhesives, binders, and polymer compounds. Mercer International produces high-quality lignin using the LignoBoost process across industrial applications, underpinned by sustainable forestry certifications that matter increasingly in procurement evaluations.
Regional specialization also shapes the field. Nippon Paper Industries stands as the only lignin manufacturer in Japan, offering a broad product range including SAN X, VANILLEX, and PEARLLEX grades for industrial uses. Domtar Corporation supplies high-purity kraft lignin under its BioChoice label from its Plymouth mill using LignoBoost, with a focus on sustainable lignin for binders and composites. West Fraser provides lignin products for bio-composites and binding agents derived from its pulp operations. Metsä Group develops modified lignin products such as Metsä LigO for concrete and other applications, expanding the scope of lignin-derived functional materials. Pure Lignin Environmental Technology Ltd. produces high-grade native-form lignin with purity levels reaching extremely high thresholds from biomass processing, targeting applications that demand specification-grade consistency. Lignin Industries develops lignin-based thermoplastics and biomaterials using patented technology to transform lignin into renewable plastics, illustrating the broader innovation curve beyond conventional extraction and purification.
Recent corporate activity highlights the pace of commercialization and partnership formation. In early 2025, LignEasy Oy shipped its first large-scale big-bag sample of a lignin-based product, signaling a transition from pilot-scale validation to early commercial distribution. Late 2024 saw Metsä Fibre develop a new lignin product at its Äänekoski demo plant for concrete applications aimed at replacing fossil-based chemicals. Mid-2024 brought a strategic partnership between Stora Enso and Altris to adapt lignin-derived hard carbon for anode material in sodium-ion batteries, expanding the addressable market into energy storage materials. Earlier in 2024, Lignin Industries raised over 2.2 million USD to strengthen its market position, expand its team, and increase manufacturing capacity for lignin-based bioplastics. These moves illustrate how the competitive field is being reshaped not only by production scale but by application innovation, partnership ecosystems, and targeted capital deployment.
Report Content and Operational Utility
The full research deliverable is structured to support concrete strategic workflows rather than abstract market commentary. It provides a comprehensive market sizing framework spanning historical years and the full 2026 to 2032 forecast period, with clear delineation between base-year validation and forward projections. Segmentation analysis covers type, application, and region, enabling users to isolate growth pools, assess substitution readiness, and identify where qualification cycles may create near-term opportunity or near-term risk.
Competitive profiling extends beyond static company summaries to include capacity positioning, technology platforms, product grade architecture, and strategic development activity. Industry context modules examine raw material availability, regulatory drivers, and processing economics, giving strategists a multi-variable lens on supply feasibility and demand durability. The report also integrates recent corporate developments, product launches, partnerships, and funding events, allowing readers to map the velocity of commercialization and detect emerging competitive threats or collaboration opportunities before they become widely priced into the market.
For commercial teams, the analysis supports application prioritization, pricing strategy, and customer qualification planning. For corporate development and investors, it offers a structured view of concentration dynamics, technology risk, and capacity expansion signaling. For sustainability and procurement functions, it provides a reference point for evaluating lignin-based alternatives against regulatory requirements, embodied carbon targets, and performance specifications.
Strategic Implications for 2026 Decision-Making
The 2026 decision environment demands a disciplined approach to market entry, partnership selection, and capacity alignment. Several strategic implications stand out.
First, value capture will increasingly attach to purity, consistency, and application-specific technical service rather than bulk availability alone. As end-users qualify lignin-based formulations in performance-sensitive markets, suppliers that can demonstrate lot-to-lot reliability, formulation support, and regulatory compliance will command stronger positioning.
Worldwide High Purity Lignin Market
Lignin Products Market
Second, partnership architecture is becoming a defining competitive variable. Collaborations that link lignin producers with downstream formulators, battery material developers, concrete additive specialists, and bioplastics manufacturers are accelerating qualification timelines and expanding addressable markets. Organizations that build or join these ecosystems early will be better positioned to shape specification standards and secure offtake alignment.
Third, regional policy intensity matters. Europe's regulatory and funding environment continues to support lignin valorization, while disclosure requirements and material substitution mandates in construction, oilfield, and industrial applications are expanding demand signals globally. Strategy teams should factor regional policy trajectories into capacity planning, go-to-market sequencing, and supplier selection.
Fourth, the market's moderate concentration profile means that both scaled incumbents and focused specialists can succeed, but via different playbooks. Incumbents leverage integrated mill economics, established recovery infrastructure, and broad grade portfolios. Specialists compete on purity ceilings, proprietary transformation technologies, and targeted application expertise. Understanding which model aligns with a given application pathway is essential for both procurement and investment decisions.
Conclusion
The high purity lignin market is transitioning from early-stage substitution interest to a more structured, specification-driven commercial landscape. The convergence of regulatory pressure, application innovation, and capacity expansion is creating a window in which informed strategic choices can materially affect competitive outcomes over the remainder of the decade. Our Worldwide High Purity Lignin Market research is designed to provide the depth, segmentation clarity, and competitive intelligence required to operate with precision in that environment.
The preview above highlights the structural framework, growth trajectory, segmentation logic, and competitive dynamics that define the market. The complete report delivers the full quantitative architecture, regional and application-level breakdowns, detailed company profiles, and forward-looking scenario analysis necessary for decisive 2026 planning. Readers seeking the complete dataset, exact segmentation values, and the full analytic toolkit are encouraged to access the full study for comprehensive market intelligence.
For detailed analysis of this topic, please visit the official page: Worldwide High Purity Lignin Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Facial Rejuvenation Market Hits $32.5B in 2025, Projected to Reach $57.5B by 2032 at 8.5% CAGR
By pmarketresearch, 2026-09-16
Navigating the Global Facial Rejuvenation Market: Strategic Intelligence for Leadership Decision-Making in 2026
The worldwide facial rejuvenation industry is entering a pivotal growth phase, driven by sustained demand for minimally invasive procedures, continuous innovation in injectables and energy-based platforms, and expanding access across both mature and emerging healthcare ecosystems. As organizations plan capital allocation, pipeline development, and competitive positioning for 2026, the need for calibrated, forward-looking intelligence has never been greater. PW Consulting’s latest research on the Worldwide Facial Rejuvenation Market is designed to equip boards, commercial leaders, and R&D strategists with precisely that capability: a structured, evidence-based view of where value is being created, how competitive dynamics are shifting, and what operational realities will shape execution over the 2026 to 2032 horizon.
Beauty Devices Market
This report does not merely track historical performance; it constructs an actionable strategic map. It integrates macroeconomic momentum, procedural adoption patterns, regulatory evolution, and competitive behavior into a coherent framework that decision-makers can use to stress-test assumptions, prioritize investments, and anticipate inflection points. Below, we outline the analytical architecture of the study and explain why it is essential reading for executives operating in aesthetic medicine, medical devices, injectables, and adjacent health-and-wellness segments.
Macro Trajectory and Market Architecture: Why the Numbers Matter Strategically
The global facial rejuvenation market established a clear upward trajectory between 2020 and 2025, with revenue advances reflecting both pent-up procedural demand and the maturation of treatment ecosystems in multiple regions. From a base-year starting point of USD 32,500 million in 2025, the sector is positioned to extend its growth into the 2026 to 2032 forecast period at a compound annual growth rate of approximately 8.5 percent. Over the course of that window, total market revenue advances toward a significantly larger scale, signaling durable expansion rather than a short-cycle uplift.
For leadership teams, these figures are more than directional indicators. They frame the scale of opportunity, the pace at which share can shift, and the timing at which new entrants or product extensions can realistically influence category economics. Our analysis translates this trajectory into strategic implications: where demand is structurally expanding, where growth is increasingly competitive, and where operational or regulatory friction may moderate realized returns even when procedural volume remains strong.
Equally important, the report examines how value is distributed across product categories and end-user channels without reducing the market to a static snapshot. Botulinum toxin, dermal fillers, energy-based devices, chemical peels, and microdermabrasion and related approaches each follow different adoption curves, reimbursement realities, and practitioner preferences. This heterogeneity matters for portfolio strategy. A product or device positioned in one segment may face a substantially different competitive and commercial environment than a comparable offering in another, even within the same geography or clinical setting. Our segmentation analysis highlights those distinctions and shows how growth leadership is migrating as patient expectations, clinician training, and technology accessibility continue to evolve.
Worldwide Facial Rejuvenation Market
The same logic applies to end-user demand patterns. Dermatology clinics, medical spas, and hospitals each represent distinct commercial environments with different purchasing behaviors, service models, patient demographics, and regulatory considerations. Understanding how these channels interact, where they compete for procedures, and where they complement one another is essential for go-to-market planning, distribution strategy, and service-line development. The report maps these relationships and identifies the demand nodes that matter most for both established operators and new entrants.
From Insight to Execution: What the Report Delivers
PW Consulting’s facial rejuvenation study is built for practitioners of strategy, not simply for readers of summaries. It provides a comprehensive decision-support toolkit that covers the operational, commercial, and competitive dimensions most relevant to 2026 planning. Key components include:
- An integrated view of historical performance from 2020 through 2025, combined with a detailed forecast structure for 2026 to 2032, allowing leadership teams to evaluate momentum, cyclicality, and segment-specific growth potential.
- A granular segmentation framework that breaks the market down by product type and by end-user setting, enabling more precise scenario planning, pricing strategy, and channel prioritization.
- A regional perspective that identifies where demand is concentrated, where procedural ecosystems are maturing, and where growth conditions are changing most rapidly, without reducing complex local dynamics to oversimplified rankings.
- A competitive landscape assessment that profiles the leading companies shaping categories, illustrates how portfolios are constructed, and explains which strategic moves are likely to influence the next phase of consolidation, differentiation, and capability-building.
- A practical set of market dynamics, covering regulation, reimbursement, safety oversight, practitioner qualification, and technology adoption, all of which directly affect commercialization planning and long-term category viability.
Beyond data presentation, the report is organized to answer the questions that executives actually face. Which product categories and end-user channels will generate the most durable revenue growth? Where should organizations invest in training, clinical evidence, and practitioner engagement? How do regulatory expectations and safety communications alter device and injectable strategy? Which competitive behaviors suggest that share shifts will be determined by innovation, access, and service quality rather than by scale alone? The study provides analytical depth on each of these themes so that leaders can build plans that are resilient to uncertainty and responsive to structural opportunity.
Competitive Landscape: Portfolio Logic, M&A, and Innovation Posture
The facial rejuvenation arena is shaped by companies that compete across injectables, energy-based devices, and related aesthetic platforms. Rather than treating competitors as isolated brand names, the report examines them as strategic actors with differentiated assets, geographic footprints, clinical evidence bases, and commercial architectures. This perspective is critical because competitive advantage in this market often depends on more than product performance alone. It also depends on training access, clinical credibility, indication expansion, distribution strength, and the ability to align product portfolios with patient and practitioner expectations.
Several major players illustrate the diversity of strategic positioning in the category. AbbVie, through its Allergan Aesthetics franchise, maintains a prominent role in neuromodulators and hyaluronic acid dermal fillers, supported by established brand recognition and broad practitioner familiarity. Galderma competes with a portfolio spanning hyaluronic acid fillers, biostimulatory options, and neuromodulators, while also pursuing indication development and regulatory milestones that extend the clinical utility of its platforms. Merz Pharma contributes neuromodulators and a range of filler technologies aimed at wrinkle reduction and volume restoration. Revance Therapeutics, following its acquisition by Crown Laboratories, represents a notable example of portfolio consolidation, bringing a longer-duration neuromodulator platform and resilient hyaluronic acid fillers into a broader skin-health and aesthetics ecosystem.
On the device side, the market includes a broad field of companies developing lasers, intense pulsed light systems, radiofrequency platforms, and microneedling-based technologies. Lumenis, Cynosure, Candela, Cutera, Alma Lasers, Sciton, Lutronic, and Hologic through its Solta Medical franchise all participate in the energy-based device segment with platforms designed for skin resurfacing, tightening, and photorejuvenation. Their competitive positioning depends not only on hardware performance, but also on procedural efficiency, treatment customization, clinical support, and integration into service workflows across dermatology and medical spa settings.
Additional participants broaden the competitive fabric further. Bausch Health, Anika Therapeutics, Contura International, Suneva Medical, Teoxane, and Sinclair Pharma each contribute products or technologies relevant to injectables, regenerative approaches, and facial contouring, reinforcing the market’s multi-layered structure. For strategists, this landscape conveys an important message: leadership is contested across multiple fronts, and competitive advantage increasingly arises from portfolio breadth, evidence generation, and the ability to support safe, effective, and consistent treatment delivery.
Recent industry activity underscores how quickly these strategic dynamics are evolving. In early 2026, Galderma secured FDA approval for Restylane Contour for temple hollowing correction in patients over 21, expanding the indication scope for volume restoration and facial balance. Around the same time, the company presented new data on Sculptra’s regenerative properties for face and body at IMCAS 2026, alongside updates on Restylane products and the Relfydess neuromodulator, while also advancing EU MDR certification expansion to additional body areas. These moves highlight how clinical data, regulatory positioning, and indication breadth can reinforce portfolio value. Elsewhere, AbbVie opened its third state-of-the-art AMI training center in Austin, signaling continued investment in practitioner education and service quality for facial rejuvenation procedures. In a major consolidation move, Crown Laboratories completed the acquisition of Revance Therapeutics for USD 924 million, integrating the DAXXIFY neuromodulator and RHA filler platforms with its skin health portfolio to strengthen facial aesthetics offerings. More recently, Dermalogica launched its PRO Pen Microneedling System, marking its first FDA-cleared medical aesthetic device for improving facial acne scars and illustrating how facial rejuvenation and skin-quality technologies continue to converge.
Market Dynamics That Will Shape Strategy in 2026
Commercial strategy in facial rejuvenation cannot be separated from the evolving regulatory and operational environment. The report devotes substantial attention to dynamics that influence demand, product development, device selection, and market access, because these forces often determine whether growth assumptions hold in practice.
Regulatory oversight remains a central theme. The FDA’s October 2025 safety communication drew attention to potential risks such as burns, scarring, and nerve injuries linked to certain uses of radiofrequency microneedling devices, especially when unregulated devices or unlicensed operators are involved. For device manufacturers, clinical educators, and service providers, this type of guidance has direct implications for training, product positioning, clinic protocols, and risk communication. It also reinforces why procedural safety and practitioner qualification are not peripheral concerns but core elements of credible market expansion. In parallel, ongoing compliance requirements under the Modernization of Cosmetics Regulation Act continue to shape obligations for cosmetic product facilities, including biennial registration and listing, updated FDA portal functionality, and advancing GMP-related expectations across 2025 and 2026.
Reimbursement and payment dynamics add another layer of strategic realism. Most facial rejuvenation procedures using neuromodulators, dermal fillers, and laser resurfacing are generally treated as elective cosmetic treatments and are not covered by public or private health insurance, with limited exceptions for medically necessary applications such as chronic migraine therapy. This reality influences patient acquisition models, pricing strategies, financing options, and the broader economics of service delivery. It also means that demand resilience can be sensitive to consumer discretionary spending, perceived treatment value, and the credibility of outcomes. Leaders who plan growth must therefore account for both clinical adoption and the financial behaviors of the end patient.
Licensing and procedural oversight are also evolving in key jurisdictions. In the UK, governments in England and Scotland have advanced consultations and proposed risk-based licensing systems for non-surgical cosmetic procedures, including potential minimum age requirements and tiered restrictions, with additional consultations expected in 2026. These developments illustrate how policy can reshape operating conditions, practitioner standards, and market access over time. Combined with the longstanding expectation that many injectable and filler procedures require administration by licensed physicians or properly qualified practitioners under FDA and local medical board oversight, the message is clear: commercial success in this space depends on disciplined clinical governance, credible training, and operational consistency.
How Leaders Should Use This Research
The strategic value of this study lies in its ability to convert complex market information into decision-ready insight. For portfolio and R&D teams, the segmentation and category analysis provide a foundation for prioritizing development efforts, evaluating indication opportunities, and understanding where clinical differentiation can translate into commercial advantage. For commercial and distribution leaders, the end-user and regional analyses support channel strategy, partnership evaluation, and training investment decisions. For competitive intelligence and corporate development teams, the company profiles and recent market moves create a basis for benchmarking, positioning, and assessing consolidation or partnership opportunities.
Equally important, the report’s treatment of regulation, reimbursement, and safety dynamics helps organizations test their growth plans against operational reality. A compelling product or device concept can still face headwinds if training, compliance, clinician confidence, or patient trust are not addressed systematically. By integrating these considerations into the market narrative, the research enables leaders to build strategies that are not only ambitious but also executable.
Next Steps
The Worldwide Facial Rejuvenation Market is expanding within a landscape defined by technological innovation, evolving regulation, contestable competitive positions, and changing patient expectations. Organizations that want to act with confidence in 2026 need more than top-line figures; they need a rigorous, structured view of how demand is formed, how value is distributed, and how strategic moves by peers are reshaping the category. PW Consulting’s full market research delivers that depth, with comprehensive segmentation, forecast detail, competitive profiling, and regulatory and operational context designed for executive use.
To explore the complete dataset, segment-level forecasts, regional breakdowns, and competitive analysis in full, we invite you to access the source report and accompanying materials. The detailed intelligence within the study is intended to support strategic planning, investment prioritization, and market-entry evaluation with the precision required for high-stakes decision-making in the years ahead.
For detailed analysis of this topic, please visit the official page: Worldwide Facial Rejuvenation Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com